
Correcting a return of earnings submitted incorrectly
21 August 2026
Correcting an incorrect return of earnings requires a supported request to the Compensation Fund, with payroll evidence showing the original error and the correct earnings.
Correcting an incorrect Compensation Fund return of earnings requires submitting a formal revision application supported by verified payroll records and a sworn affidavit within the Department’s applicable administrative revision period.
When a South African employer discovers an error on a submitted Return of Earnings (ROE) form WAS.8, the online system locks the declaration, preventing direct online edits on the portal 1 2.
Rectifying misstated employee earnings, misclassified director remuneration, or erroneous headcounts requires navigating primary legislation under the Compensation for Occupational Injuries and Diseases Act (COIDA) 130 of 1993 3 4 and the COIDA Amendment Act 10 of 2022 5 6, as well as administrative protocols issued by the Department of Employment and Labour 7 8. Employers must distinguish statutory obligations from regulatory guidance, supported by professional compliance oversight from Evolv Accountants.
Amended earnings evidence and original declaration
Use the ROE period and submission window prescribed for the relevant season. The Department’s2026 notice opened the 2025 ROE season from 1 April to 30 June 2026.
Assemble actual earnings for the period requested and the provisional figures required by the return; do not apply31 March as a universal current portal deadline. Official2026 ROE notice.
Common errors on an original declaration include under-declaring gross employee wages, miscalculating executive director remuneration, omitting overtime or bonus payments of a regular nature 11, or making arithmetic misstatements across operating locations 2 4. The material consequence of an uncorrected error depends on whether earnings were under-stated or over-stated:
- Under-declared earnings: Correct the actual earnings and inspect the legal basis of any penalty. The original section 82(3) and the amended section 83(6) address different circumstances and bases; section 83(6)(c) concerns the assessment difference when actual earnings exceed estimated earnings. Do not calculate every penalty as10% of the earnings shortfall. Amended section 83.
- Audit blocks and clearance delays: Discrepancies trigger an audit block on the employer's profile 16. An audit block prevents the generation of a Letter of Good Standing (LoGS) 16, restricting the enterprise from bidding on commercial tenders or engaging principal contractors and main contractors 17.
- Material misstatements: Knowingly making a false statement in any return or report to the Compensation Fund constitutes a statutory offence under Section 98 of Act 130 of 1993 18. Over-declared earnings result in inflated assessment billings, draining business cash flow until formally revised 1 19.
Preserve the original records: amended earnings evidence
Before initiating a formal correction, an employer must secure all historical documentation relating to the original declaration and compile robust amended earnings evidence 7 8.
Section 50 of the COIDA Amendment Act 10 of 2022 substitutes section 81. The current retention requirement is at least five years after the last entry in the earnings register or other prescribed record 5 21.
Failure to retain records as required attracts an administrative penalty not exceeding 10 per cent of actual or estimated annual assessments for the non-compliant period 21. Amended COIDA section 81; 2026 commencement dates.
Employers must retain the following original records and access credentials without alteration 3 10 22:
- The original WAS.8 return submission confirmation and system-generated invoice 1 2.
- System access and submission logs and authorised representative assignments; keep passwords and other login secrets outside the document pack 22 23.
- Primary source documentation, including monthly payroll summary reports, employee wage registers, and annual financial statements 7 8.
History must never be erased or overwritten. An employer must maintain an unbroken audit trail that demonstrates how the original error occurred and proves the authenticity of the amended earnings evidence 7 8.
Choose the correct amendment route: original declaration
Employers must select the appropriate procedure based on whether they are requesting a routine correction, responding to an assessment notice, or lodging a statutory dispute. Official regulator guidance strictly limits online functionality:
"Once the Earnings are submitted and are incorrect, you will not be able to correct them online in the Website" 1.
Route 1: Application for Revision of Assessment
When an employer identifies an error in a submitted declaration, regulatory guidance requires submitting a formal Application for Revision of Assessment 24. The employer must submit this application within 30 calendar days from the date of the Notice of Assessment or Invoice 24.
Route 2: Annual Assessment Adjustment by Commissioner
Under Section 83(5) of COIDA (as amended by Act 10 of 2022), if actual earnings paid in a particular period differ from current estimated earnings shown in the return, the Commissioner is empowered to adjust the assessment accordingly 6.
Route 3: Statutory Objection under Section 91
If an assessment or revision decision is disputed, distinguish the administrative revision request from a statutory section 91 objection. The2026-commenced amendment provides12 months after the decision to lodge an objection, with the prescribed process and possible good-cause extension.
Check the actual decision date and current objection requirements; do not rely on the 90-day period in the original1993 Act. Amended section 91; Commencement dates.
Operational Exception: Regulator guidelines stipulate that if a business has closed, ceased operations, changed its business nature, or been liquidated, the employer must not submit returns or revisions online 8.
Make and verify the correction: amended earnings evidence
To execute an approved amendment, the employer must compile and submit a standardised audit clearance pack to the Department of Employment and Labour 7 8.
Approved Change Sequence
- Reconcile Payroll to SARS Filings: Extract detailed personnel-level payroll reports and cross-check gross taxable earnings against South African Revenue Service (SARS) EMP501 bi-annual/annual reconciliations 7 8.
- Complete Manual Declaration: Complete and sign a manual Return of Earnings form (WAS.8) displaying the accurate earnings figures and employee counts 8.
- Execute Sworn Affidavit: Draft a detailed affidavit signed before a Commissioner of Oaths, explicitly stating the correct figures and setting out the reason for the original error 7 8.
- Assemble Audit Supporting Pack: Collate the mandatory evidence pack, comprising:
- SARS EMP501 reconciliation or Tax Clearance Certificate 7 8.
- Proof of registration with the Unemployment Insurance Fund (UIF) 7.
- Detailed payroll report itemised by employee 7 8.
- Audited, independently reviewed, or compiled Annual Financial Statements 7 8.
- A signed Power of Attorney if an accounting firm or consultant represents the employer 7 8.
- Formal Submission: Submit the full electronic package to the dedicated Compensation Fund audit address (2019ROE.Audits@labour.gov.za) or hand-deliver physical copies to the nearest Labour Centre 7 29.
Verification of the correction requires receiving a revised Notice of Assessment/Invoice from the Compensation Fund, confirming the removal of any profile audit blocks, and retrieving an updated Letter of Good Standing 16 30.
Consequences and remaining exceptions: original declaration
Correcting an ROE declaration carries downstream impacts across payroll, taxation, and statutory reporting:
- Tax and Payroll Alignment: Adjustments to declared earnings must be reconciled to SARS and UIF records, with legitimate definition or period differences explained 7 8. Keep evidence explaining differences between COIDA and SARS figures for any review 7.
- Payment Allocation and Contract Accounts: If a correction results in a revised assessment payment, the employer must quote the correct 99-prefixed Contract Account number as the deposit reference 1 31. Unallocated payments resulting from incorrect references must be submitted with proof of payment to Clarification@labour.gov.za 30.
- Missing Documentation Exception: If an employer lacks complete historical records, regulator guidelines permit submitting an application for estimation printed on the company letterhead alongside a supporting affidavit 32.
- Compliance Orders: Under Chapter XA (inserted by Act 10 of 2022), Compensation Fund inspectors possess statutory powers to inspect documents, issue compliance orders under Section 93F, while the Commissioner may apply to the Labour Court under section 93G to make a compliance order an order of court 33 34 35.
Next steps for COIDA and compensation
Employers should appoint an internal control owner—such as a Financial Controller or Payroll Lead—to perform annual pre-submission checks before the applicable published ROE deadline 3 9.
Operational Correction Checklist
- Identify the earnings discrepancy between internal payroll registers and the submitted WAS.8 declaration 7 10.
- Secure original submission receipts, system logs, and representative authority records 22 23.
- Draft a sworn affidavit detailing the true earnings and the cause of the misstatement 7 8.
- Populate a manual WAS.8 ROE form with verified figures 8.
- Collate SARS EMP501 forms, detailed payroll reports, UIF proof, and Annual Financial Statements 7 8.
- Execute a Power of Attorney if engaging Evolv Accountants as your representative 7 8.
- Submit the audit pack to 2019ROE.Audits@labour.gov.za within 30 calendar days of assessment issuance 7 24.
- Verify receipt of the revised assessment and obtain an updated Letter of Good Standing 16 30.
Artefact: Correction Audit Trail
| Illustrative record | Error or query | Supported action | Completion check |
|---|---|---|---|
| Submitted ROE | Payroll evidence shows understated or overstated earnings | Prepare the Fund’s required revision bundle within the applicable administrative period; distinguish a statutory objection | Retain the request and the actual revised assessment or decision |
| Employer account | Audit query prevents LOGS retrieval | Employer or appointed representative supplies the requested payroll, financial and authority documents through the prescribed route | Record the Fund’s decision; submission alone is not clearance |
| Bank payment | Correct assessment paid with a wrong or missing account reference | Send proof and correct CF reference through the published allocation-query route | Check the actual account credit and any remaining balance |
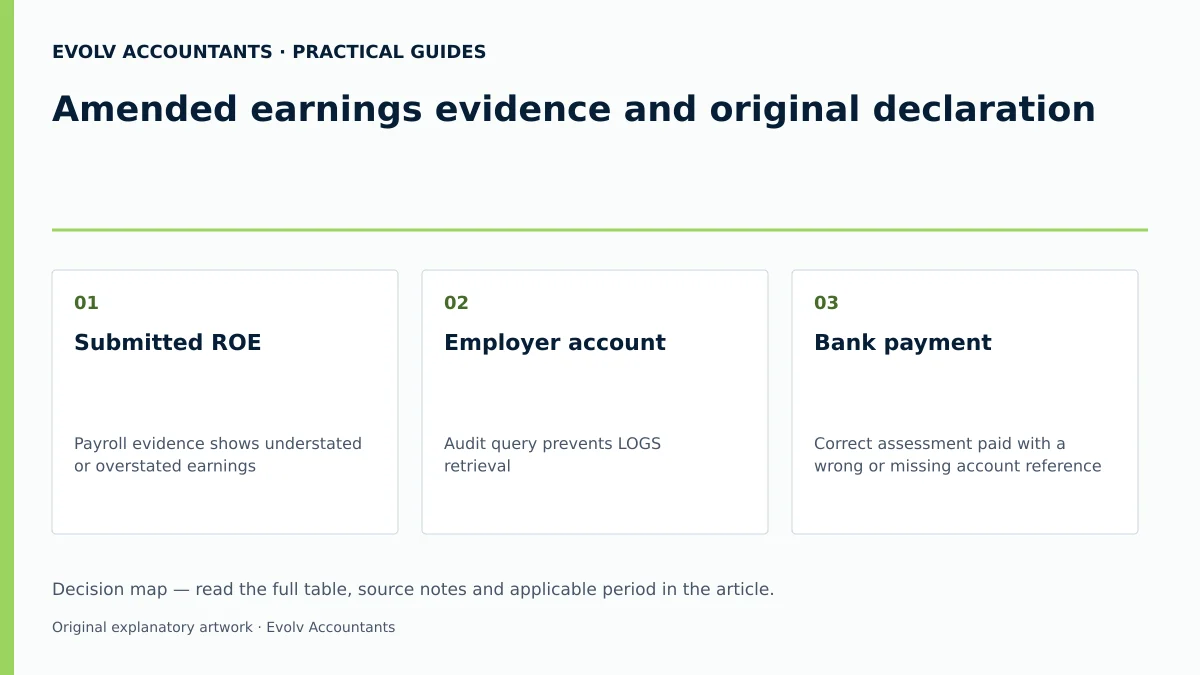
Official guidance; Official COIDA provisions.
Reproducible Hypothetical Example
Consider an SME in the manufacturing sector that submitted its annual Return of Earnings but subsequently identified an arithmetic error in its payroll reconciliation:
- Original Declared Earnings: R2,500,000 2
- Actual Audited Earnings: R3,000,000 2
- Under-Declared Discrepancy: R500,000 2 12
- Illustrative Assessment Tariff Rate: 1.5% (R1.50 per R100 earnings) 19
Calculation Breakdown:
- Additional Assessment Liability: R500,000 × 1.5% = R7,500 19.
- Penalty basis: Inspect the actual notice and provision. Amended section 83(6)(c) concerns the assessment difference following an estimate, not ten per cent of the earnings shortfall; do not combine it with a different statutory understatement rule.
- Penalty Amount: 10% × R500,000 = R50,000 12 13.
- Total Revised Additional Amount Due: R7,500 (assessment) + R50,000 (penalty) = R57,500 plus statutory interest 13 15.
A supported revision application enables the Fund to consider the correction. Check its decision, revised assessment and any separate audit query; submission alone does not clear an audit block 7 24.
Frequently Asked Questions
Can an employer correct an ROE declaration online after submitting it on the portal?
No. Once a return of earnings is submitted and confirmed on the ROE website, it cannot be corrected directly online 1 2. The employer must submit a formal application for revision supported by manual documentation 7 8.
What is the deadline for applying to revise an incorrect Compensation Fund assessment?
An employer must submit an application for revision of assessment within 30 calendar days from the date of the Notice of Assessment or Invoice 24.
How long must a business retain COIDA payroll records and earnings declarations?
Under Section 81 of COIDA Act 130 of 1993, records had to be kept for four years 3. Section 50 of the COIDA Amendment Act 10 of 2022 extends this requirement to at least five years 5 21.
What supporting documents are required to correct an earnings error with the Compensation Fund?
The employer must submit a signed manual WAS.8 form, a sworn affidavit, SARS EMP501 forms or Tax Clearance, a detailed payroll report, Annual Financial Statements, UIF proof, and a Power of Attorney if represented by an agent 7 8.
What penalty applies if an employer under-declares employee earnings?
The penalty depends on the applicable provision and facts. In particular, amended section 83(6)(c) concerns the assessment difference following an estimate, not10% of the earnings difference. Inspect the Fund’s notice and distinguish that rule from other understatement or non-payment provisions. Amended COIDA. Describe your registration or earnings-record question and ask Evolv about the support required. Ask Evolv about amended earnings evidence and original declaration. Share the relevant records so the support required can be scoped.
Related guides
- Reconciling a COIDA assessment to payroll
- When an employer must register with the Compensation Fund
- Compliance and Regulations: Keeping Your Business on Track
Sources
- https://www.labour.gov.za/DocumentCenter/Publications/Compensation%20for%20Occupational%20Injuries%20and%20Diseases/Return%20of%20Earnings%20User%20Manual%2C%20August%202019.pdf
- Compensation for Occupational Injuries and Diseases Act 130 of 1993 — original Act
- https://www.gov.za/sites/default/files/gcis_document/202304/48431-17-4-compensationoccupinjuriesdiseasesamendact10of2022a.pdf
- Compensation Fund: obligations of the employer
- https://www.labour.gov.za/DocumentCenter/Publications/Compensation%20for%20Occupational%20Injuries%20and%20Diseases/Notice%20of%20Temporary%20ROE%20Online%20Systems%20Shut-Down%20from%2019%20March%20to%2031%20March%202026.pdf
- Compensation for Occupational Injuries and Diseases Amendment Act 10 of 2022 (English / Afrikaans) | South African Government
- How To Submit Earnings Statements to the Compensation Fund