
Preparing for a SARS VAT registration verification
17 October 2025
Preparing for a SARS VAT registration verification requires assembling primary trading evidence to validate business activity and operational compliance.
When a South African small or medium enterprise (SME) submits a Value-Added Tax (VAT) registration application on South African Revenue Service (SARS) eFiling or via a branch appointment, SARS evaluates the submission through an automated risk engine 1. If a risk profile is flagged, SARS issues a Registration Application Review Notice, initiating a mandatory verification process 1.
To successfully complete verification, the applicant must submit acceptable, verifiable documentation substantiating the business's trading status and financial activity within 21 business days 1 2.
Verification pack tied to the stated trading activity
This guidance is structured for South African SME business owners, directors, public officers, and financial managers operating within the Republic of South Africa. The verification process applies to the trailing 12-month historical trading period or a prospective 12-month contractual window, depending on whether the business applies under compulsory or voluntary registration criteria 3 4 5.
Documented completion of a VAT registration verification does not mean simply submitting form WRAV01 or uploading documents onto eFiling 1. Real completion occurs only when SARS reviews the submitted verification pack, confirms the operational validity of the enterprise, validates the banking particulars, and issues an official SARS Notice of Registration reflecting an active VAT reference number 1 6 7.
Evolv Accountants recommends establishing an audit-ready verification pack prior to submitting the initial application, ensuring that declared business activity codes align directly with executed trading records 8 9 10.
— Practical point from this guide
Prepare the information and authority: verification pack tied to the stated trading activity
Preparing a verification pack requires assembling legal authority documents, representative taxpayer disclosures, proof of business address, validated banking details, and acceptable evidence of taxable supplies 8 10 11.
Statutory authority and representative vendor
SARS requires every entity applying for VAT registration to designate a representative vendor (such as a public officer for a company or a main partner for a partnership) who must be a natural person resident in South Africa 12 13 14. If a registered tax practitioner or external representative submits the application or presents documents on behalf of the business, a formal SARS Power of Attorney (POA) and proof of identity must be attached 15 16.
Distinguishing acceptable and unacceptable financial evidence
SARS enforces strict evidence boundaries when evaluating whether an enterprise has met the trading criteria for VAT registration 10 17.
- Acceptable supporting evidence includes:
- Copies of tax invoices issued for trading goods or services 10.
- Signed commercial contracts or written agreements detailing contractual obligations 10.
- Signed lease agreements where the lessor and lessee are separate legal entities 10.
- Signed financial statements or audited trading records 10.
- Official notifications confirming an awarded tender 10.
- Proof of taxable supplies made by the seller where a business is acquired as a going concern 10.
- Unacceptable evidence includes:
- Business plans or speculative non-factual proposals 17.
- Cash flow projections or financial forecasts 17.
- Purchase orders placed without corresponding proof of actual delivery or supply 17.
- Tender proposals prior to an official contract award 17.
Threshold position: law versus administrative guidance
A statutory distinction exists between SARS's current operational administration and older legislative guides:
- Compulsory registration position: SARS's current registration guidance administers compulsory VAT registration when taxable supplies exceed or are likely to exceed R2.3 million in a consecutive 12-month period 3 4 18. Older SARS publications (such as the VAT 404 Guide for Vendors) cite the historical R1 million threshold 19 20. SARS applies the R2.3 million threshold as its operational administrative position 18.
- Voluntary registration position: SARS's current operational guidance administers voluntary VAT registration where taxable supplies have exceeded R120 000 in the past 12 months, or where an average of R4 200 per month in taxable supplies is proven over a minimum of 2 months 5 21. Older guides cite a historical R50 000 threshold 22 23 24.
Evolv advises clients to prepare verification documentation that satisfies SARS's active operational thresholds while maintaining full accounting records for 5 years as required by tax law 18 25 26.
Complete the task step by step: documented completion and exceptions
To complete a SARS VAT registration verification without administrative rejection, SMEs should follow a structured execution sequence grounded in primary SARS instructions 1 2 6 8 27 28.
Sequenced verification execution process
- Initiate registration form WRAV01: Access eFiling under SARS Registered Details -> Maintain SARS Registered Details (or schedule a virtual/branch appointment) 6 27.
- Populate the VAT container: Complete all required entity particulars, select the correct business activity code from the VAT 403 trade classification guide, declare the liability date, and select the accounting basis (invoice basis is standard; payments basis requires specific qualifying criteria) 8 9 29.
- Submit and authenticate: Submit form WRAV01 on eFiling and complete the required facial biometric authentication where prompted 1 27.
- Receive status notification:
- Immediate allocation: If SARS flags no risk, a VAT number is allocated immediately 6.
- Review notice: If selected for verification, SARS issues a Registration Application Review Notice on eFiling outlining the required verification pack 1.
- Compile and upload verification pack: Gather all requested primary documents and upload them via eFiling or the SARS Online Query System within 21 business days from the notice date 2 28.
- Branch verification appointment (if required): Where an in-person interview or branch verification is requested, the representative vendor must present original identification and A4 document copies referencing the SARS case number 2 28.
Check the result against the evidence: verification pack tied to the stated trading activity
Submitting supporting documents does not equate to SARS accepting the VAT registration 1. Independent completion evidence must be verified directly through official SARS channels 7 30 31.
Verifying independent completion
To confirm that SARS has approved the verification pack and activated the VAT registration:
- Request Notice of Registration on eFiling: Log into the eFiling profile, navigate to SARS Registered Details, and select Notice of Registration -> VAT 7. The download of an official Notice of Registration containing an active 10-digit VAT reference number serves as primary proof of completion 7 32.
- Perform online vendor search: Verify the registration status independently on the public SARS VAT Vendor Search portal by entering the entity's registered details 30 31.
- Validate banking registration status: Confirm on eFiling that the entity's South African bank account details have passed SARS verification without outstanding validation flags 1 8 33.
Handle exceptions and unresolved cases: documented completion and exceptions
When navigating SARS VAT verification, specific administrative edge cases and exceptions may arise that require specialist intervention.
Missing documentation deadline
If the verification pack is not submitted within 21 business days of the Registration Application Review Notice, SARS will automatically reject the application 2. If an application is rejected, the business must initiate a new WRAV01 submission 2 27.
SARS generally requires banking details in the vendor’s name. Specified third-party banking exceptions include foreign/non-resident companies and qualifying holding/subsidiary group companies, subject to VAT119i and the supporting evidence required by SARS.
Backdating liability dates
For compulsory registrations, eFiling permits automated backdating of the VAT liability date up to a maximum of 6 months from the date the compulsory threshold was exceeded 37. If compulsory backdating exceeds 6 months, or if a vendor requests backdating for a voluntary registration, the system will block automated processing, requiring an in-person branch appointment with historical financial statements, contracts, and issued invoices 37.
Distinguishing verification from audit
A SARS verification is a targeted document review limited to evaluating the accuracy of a single registration application or return 38 39. It differs from a formal SARS compliance audit, which involves a comprehensive audit of accounting records across multiple tax periods 39. If SARS escalates a verification into a formal audit or issues an assessment dispute,
Next steps for VAT registration
Reusable preparation checklist
- Confirm that the representative vendor is a natural person residing in South Africa and that public officer details are up to date with SARS 12 14.
- Calculate trailing 12-month taxable turnover to verify whether the business meets the compulsory threshold (R2.3m administrative position) or voluntary criteria (R120 000 / R4 200 monthly average) 4 5 21.
- Obtain an official bank stamped letter or statement (not older than 3 months) matching the entity's registered name 8 40.
- Assemble primary trading proof (signed contracts, invoices issued, or signed lease agreements); discard unacceptable items such as cash flow forecasts or business plans 10 17.
- Submit form WRAV01 on eFiling, complete facial biometric authentication, and check correspondence daily for a Review Notice 1 27.
- Upload the complete verification pack within 21 business days and download the final Notice of Registration upon approval 2 7.
Reproducible hypothetical example
Scenario: SME Alpha (Pty) Ltd provides IT consulting services in Johannesburg. For this hypothetical example, assume the 12 trading months run from April 2026 to March 2027, with no earlier enterprise activity or registration liability. The business reviews those records to determine its VAT registration obligation.
- Illustrative monthly trading turnover (standard-rated supplies at 15% VAT):
- Months 1 to 10: R180 000 per month (Total: R1 800 000) 41.
- Month 11: R280 000 41.
- Month 12: R250 000 41.
- Total trailing 12-month taxable supplies: R2 330 000 4 41.
Assessment & Action:
- Threshold evaluation: The total taxable turnover of R2 330 000 exceeds the SARS administrative compulsory threshold of R2.3 million 3 4 18.
- Obligation window: Alpha (Pty) Ltd must submit a compulsory VAT registration application within 21 business days of exceeding the threshold 4.
- Verification pack preparation: Alpha compiles 12 months of issued tax invoices (totalling R2 330 000), executed client service agreements, an original bank statement, and company registration documents 10.
- Outcome: Upon submitting form WRAV01 on eFiling and uploading the verification pack in response to the review notice, SARS verifies the trading activity and issues a Notice of Registration allocating a VAT reference number 1 6 7.
Task and completion checklist
| Step | Input or evidence | Responsible person | Completion check | Exception or next action |
|---|---|---|---|---|
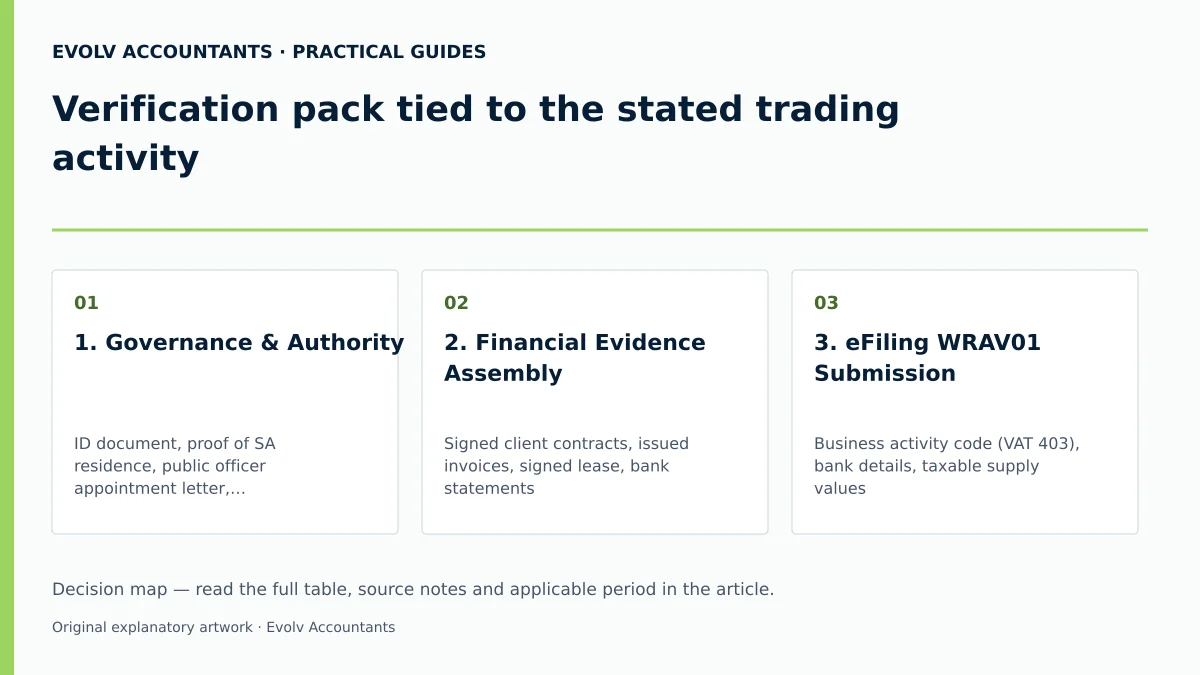
| 1. Governance & Authority | ID document, proof of SA residence, public officer appointment letter, tax practitioner POA 12 15 | Public Officer / Representative Vendor | Registered details updated on SARS profile 27 | Appoint resident representative vendor if non-resident 12 |
| 2. Financial Evidence Assembly | Signed client contracts, issued invoices, signed lease, bank statements 10 | Financial Manager / Accountant | Turnover verified against R2.3m compulsory or R120k voluntary criteria 4 21 | Remove unacceptable non-factual forecasts or draft tenders 17 |
| 3. eFiling WRAV01 Submission | Business activity code (VAT 403), bank details, taxable supply values 8 | Representative Vendor / Tax Practitioner | Submission confirmation and biometric completion if prompted 1 27 | Schedule branch appointment if eFiling blocks backdating >6 months 37 |
| 4. Verification Pack Upload | Registration Application Review Notice, case number, compiled PDF pack 1 2 | Tax Practitioner / Financial Manager | Upload receipt generated on eFiling / Online Query System 2 28 | Ensure submission within 21 business days to avoid rejection 2 |
| 5. Registration Finalisation | eFiling Notice of Registration download, VAT Vendor Search confirmation 7 30 | Business Owner / Public Officer | Active 10-digit VAT number verified on official SARS system 7 30 | Follow up with SARS using the case number if the review remains unresolved 2 |
Frequently Asked Questions
How long does SARS take to issue a VAT number once supporting documents are uploaded?
Where no risk is flagged by the automated system, SARS issues a VAT reference number immediately 6 30. If selected for verification, SARS requires supporting documents to be submitted within 21 business days, and processing depends on document validation and potential premises inspection 1 2 28.
Can I use projected cash flows or a business plan to prove my turnover for VAT registration?
No. SARS explicitly excludes non-factual plans, business plans, cash flow projections, and unawarded tender proposals from acceptable evidence of taxable supplies 17. Applicants must provide objective proof such as signed contracts, issued invoices, or signed lease agreements 10.
What happens if I miss the 21-day deadline to submit my verification documents?
Failure to submit the required supporting documents within 21 business days of the Registration Application Review Notice results in SARS automatically rejecting the VAT application 2. Review the rejection notice and obtain SARS instructions on the appropriate next step.
Is it possible to backdate a voluntary VAT registration?
No. SARS policy states that voluntary VAT registrations cannot be backdated; the effective date is set according to the date of application 37. Backdating a voluntary application requires presenting exceptional written justification and historical proof to SARS 37.
Can a business use its director’s personal bank account for VAT registration?
SARS generally requires banking details in the vendor’s name. Specified third-party banking exceptions include foreign/non-resident companies and qualifying holding/subsidiary group companies, subject to VAT119i and the supporting evidence required by SARS. Ask Evolv about verification pack tied to the stated trading activity. Share the relevant records so the support required can be scoped.
Related guides
- VAT registration through eFiling
- When a South African business must register for VAT
- The Proactive SARS Audit Guide: Keeping Your Business Ledger Sanitised
Sources
- Register for VAT | South African Revenue Service
- https://www.sars.gov.za/wp-content/uploads/Ops/Guides/VAT-REG-02-G01-Guide-for-Completion-of-VAT-Application-External-Guide.pdf
- https://www.sars.gov.za/wp-content/uploads/Ops/Guides/Legal-Pub-Guide-VAT404-VAT-404-Guide-for-Vendors.pdf
- Obligations of a VAT vendor | South African Revenue Service
- FAQs for VAT vendors | South African Revenue Service