
Provisional tax payment calendar for individuals
12 June 2025
Provisional tax for South African individuals is a mechanism requiring advance income tax payments across the year of assessment to prevent lump-sum debt.
Managing personal tax obligations requires strict adherence to statutory deadlines and accurate estimation of non-remuneration income. Provisional tax enables self-employed individuals, sole proprietors, partners, and corporate directors earning independent income to settle their normal income tax liability incrementally throughout the assessment year. By completing biannual IRP6 returns on SARS eFiling, taxpayers prevent administrative penalties, underestimation interest, and unexpected year-end tax liabilities.
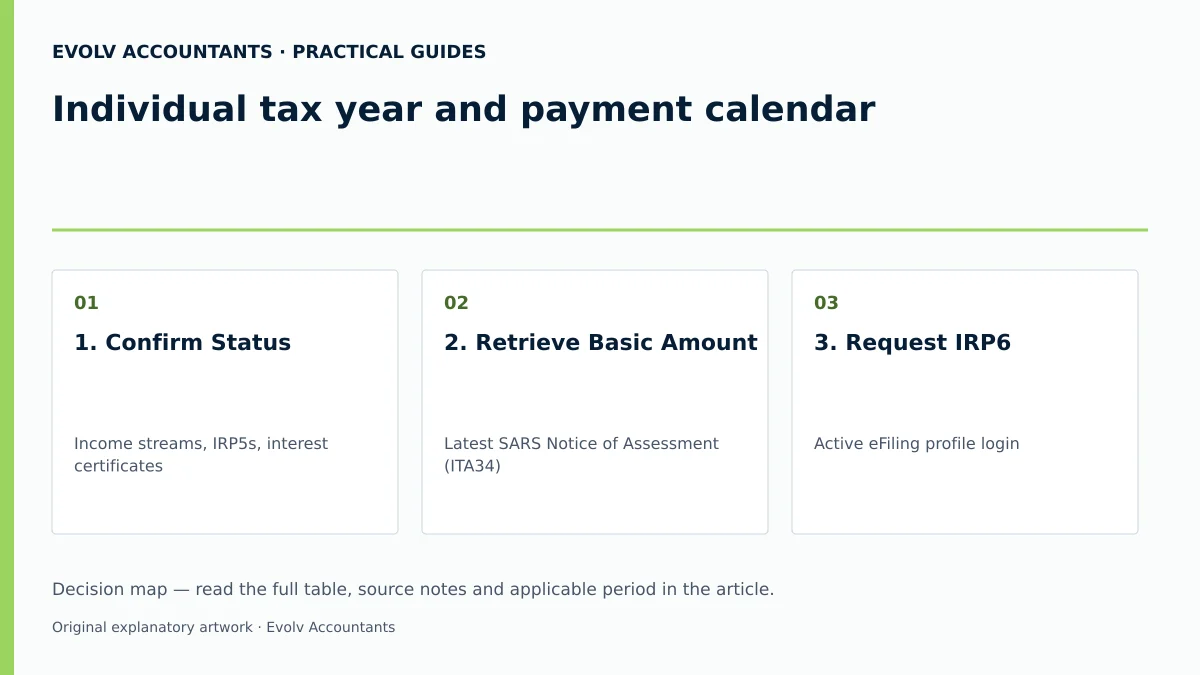
Individual tax year and payment calendar
Jurisdiction and taxpayer scope
Keep a separate diary for submitting each IRP6 return and settling the payment. A saved draft or a generated reference number does not by itself prove that the tax has been paid.
— Evolv’s practical recommendation
In South Africa, the individual tax year for natural persons runs strictly from 1 March to 28 February (or 29 February in leap years) 1 2. Provisional tax is not a separate tax type; it is an advance payment mechanism governed by the Fourth Schedule to the Income Tax Act No. 58 of 1962 3 4 5. Completing this task means accurately estimating taxable income, submitting the required IRP6 return via SARS eFiling, and settling the calculated payment by the prescribed deadline 6 7 8.
The individual provisional tax calendar
For any assessment year ending on 28/29 February, natural persons must navigate three distinct payment windows 2 3 9:
- First Provisional Tax Period (50% Payment): Due six months into the tax year, by 31 August 2 9. If 31 August falls on a weekend or public holiday, payment is due on the last business day prior 9 10.
- Second Provisional Tax Period (100% Cumulative Payment): Due on the final business day of the tax year, 28/29 February 2 9. This period accounts for total estimated annual taxable income less PAYE and first-period provisional payments 6 11.
- Third Voluntary Top-Up Period: Due by the last business day of 30 September following the end of the tax year 9 12. This optional payment allows February year-end taxpayers to settle shortfalls and reduce potential interest under Section 89quat 3 13 14.
INDIVIDUAL PROVISIONAL TAX CALENDAR
| First Period (IRP6.01) | Second Period (IRP6.02) | Third Top-Up (Optional) |
|---|---|---|
| 31 August | 28/29 February | 30 September |
| 50% of estimated annual | 100% estimated tax less | Settle tax shortfall to |
| liability less PAYE | PAYE & 1st payment | avoid 89quat interest |
Distinction between taxation regimes
Taxpayers must separate provisional tax rules from other business tax structures:
- Provisional Tax for Individuals: Applies to natural persons earning non-remuneration income, assessed using progressive individual tax brackets (ranging from 18% to 45% for the 2027 tax year) 15 16.
- Small Business Corporations (SBC): Applies exclusively to qualifying incorporated companies under Section 12E, taxed at graduated corporate rates (e.g., 0% on taxable income up to R99 000 and 7% on income between R99 001 and R365 000 for years of assessment ending between 1 April 2026 and 31 March 2027) 17 18.
- Ordinary Corporate Income Tax: A flat rate of 27% levied on companies for assessment years ending on or after 31 March 2023 through 31 March 2027 19.
- Turnover Tax: A simplified turnover-based regime under the Sixth Schedule for micro-businesses with annual turnover up to R1 million, operating outside standard provisional tax calculations 20 21.
Prepare the information and authority: individual tax year
Required documentation and system access
Before initiating an IRP6 return, individual taxpayers must assemble specific records:
- SARS eFiling Credentials: Active profile access with provisional tax registered under tax types 7 22.
- Historical Notice of Assessment (ITA34): The notice issued for the latest preceding tax year to verify the statutory basic amount 23 24.
- Income Schedules: Detailed records of business turnover, freelance fees, rental profits, foreign dividends, and taxable interest 25 26.
- Tax Deduction Certificates: IRP5/IT3(a) certificates for any employees' tax (PAYE) withheld, medical scheme contribution certificates, and foreign tax proof under Section 6quat 6 27 28 29.
Statutory definitions and exemption thresholds
SARS external guidance specifies that a provisional taxpayer includes "any person who receives income (or to whom income accrues) other than remuneration" 30. However, statutory exclusions apply under paragraph 1 of the Fourth Schedule 31 32 33:
- Tax Threshold Exclusion: A natural person carrying on no independent business is exempt if taxable income does not exceed the annual tax threshold 32 33. For the 2027 tax year (1 March 2026 – 28 February 2027), thresholds are R99 000 for taxpayers under 65, R153 250 for those aged 65 to 74, and R171 300 for those aged 75 and older 32 34. For the 2026 tax year, thresholds were R95 750, R148 217, and R165 689 respectively 34.
- Investment Income Exclusions: A natural person with no business income is exempt if taxable income from interest, foreign dividends, rental property, and unregistered employer remuneration does not exceed R30 000 per annum 25 32.
- Exempt Interest Limits: Local interest up to R23 800 for individuals under 65 (and R34 500 for those 65 and older) is exempt from income tax and does not trigger provisional tax liability 30.
- Company Directors: Directors of private companies and members of close corporations are classified as employees for PAYE purposes and are not automatically provisional taxpayers unless they earn independent business income 35 36.
Calculating the basic amount
The basic amount serves as the legal baseline for provisional estimates 23 37:
- Definition: Taxable income as assessed in the latest preceding tax year, provided the notice of assessment was issued at least 14 calendar days prior to submitting the IRP6 return 23 24.
- Mandatory Adjustments: Taxpayers must subtract taxable capital gains, retirement fund lump-sum benefits, and severance benefits from the assessed taxable income 23 38.
- The 8% Uplift Rule: If the estimate is submitted more than 18 months after the end of the latest assessed tax year, the basic amount must be increased by 8% per annum for each compounding year 39 40.
Distinguishing legal requirements, guidance, and advice
Taxpayers must recognise authority boundaries:
- Law: Fourth Schedule to the Income Tax Act No. 58 of 1962 and Tax Administration Act No. 28 of 2011 5.
- Regulator Guidance: SARS External Guides (GEN-PT-01-G01 and GEN-PT-01-G02), providing non-binding operational instructions 41 42 43.
- Evolv Recommendations: Independent professional accounting practice standards advocating conservative income estimates, early data reconciliation, and professional review.
Complete the task step by step: payment calendar
Sequenced eFiling process
Follow these official steps on SARS eFiling to complete and file the IRP6 return 22 44 45:
- Log In: Access SARS eFiling using authorised credentials 22.
- Navigate to Returns: Select Returns -> Returns Issued -> Provisional Tax (IRP6) 44.
- Request Return: Choose the applicable tax year and period from the drop-down menu (e.g., 2027-01 for August 2026 or 2027-02 for February 2027) and click Request Return 44 46.
- Open Work Page: Click on IRP6 on the Provisional Tax Work Page 46.
- Capture Financial Inputs: Enter Gross Income, Estimated Taxable Income, Medical Scheme Fees Tax Credit (Section 6A), Additional Medical Expenses Tax Credit (Section 6B), and PAYE withheld 26 47.
- System Calculations: The eFiling system auto-calculates normal tax on estimated taxable income and deducts statutory primary, secondary, or tertiary rebates based on taxpayer age 48 49.
- Submit Declaration: Click Save, open the Declaration modal, select Confirm, and click File Return 45.
- Effect Payment: Click Payments -> Pay Now -> Create Additional Payment -> select Provisional Tax (PROV), or transfer funds via internet banking using the 19-digit Payment Reference Number (PRN) 50 51 52.
- IRP6 EFILING SUBMISSION WORKFLOW
- 1. Log in to SARS eFiling (www.sarsefiling.co.za)
- 2. Select 'Returns' -> 'Returns Issued' -> 'Provisional Tax (IRP6)'
- 3. Choose Period (e.g., 2027-01) and click 'Request Return'
- 4. Enter Estimated Taxable Income, PAYE withheld, and Medical Credits
- 5. Review auto-calculated rebates and net provisional tax payable
- 6. Click 'Save' -> 'Confirm Declaration' -> 'File Return'
- 7. Generate 19-digit PRN and settle via eFiling Pay Now or Bank EFT
Reproducible hypothetical calculation example
Consider an individual taxpayer (under 65 years of age) preparing their First Provisional Tax Return (2027-01) for the 2027 tax year (1 March 2026 – 28 February 2027) 1 15 34:
- Estimated Annual Taxable Income: R400 000.
- Gross Normal Tax (2027 Individual Scale):
- Tax bracket: R383 101 to R530 200 is taxed at R79 998 + 31% of the amount above R383 100 15.
- Calculation: R79 998 + (31% × (R400 000 - R383 100)) = R79 998 + R5 239 = R85 237 15.
- Less Primary Tax Rebate (2027 Tax Year): R17 820 34.
- Less Medical Scheme Fees Tax Credit (Section 6A): Taxpayer and spouse (R376 + R376 = R752 per month × 12 = R9 024 per annum) 29.
- Net Annual Normal Tax Liability: R85 237 - R17 820 - R9 024 = R58 393.
- First Period Share (50% of Annual Liability): R58 393 ÷ 2 = R29 196.50 6 27.
- Less Employees' Tax (PAYE) Withheld (First 6 Months): R10 000 27.
- Net First Provisional Tax Payment Due (31 August 2026): R19 196.50 27.
Check the result against the evidence: individual tax year
Independent completion verification
Taxpayers must verify successful filing rather than assuming transmission equals processing 46 53:
- Work Page Status: Confirm that the eFiling status on the Provisional Tax Work Page reads Filed through eFiling 46.
- Provisional Tax Statement of Account (PTAX SOA): Navigate to the Provisional Tax Work Page and click Request Statement of Account 53 54. Select the relevant tax year to confirm that the submitted payment and declaration reflect correctly against SARS records 54.
- Payment Clearance Evidence: Obtain an official bank transaction receipt referencing the exact 19-digit Payment Reference Number (PRN) and SARS beneficiary ID 50 52. Allow two to five days for electronic banking clearance 10.
- Year-End Assessment Reconciliation: Upon completing the annual income tax return (ITR12), verify on the Notice of Assessment (ITA34) that all provisional payments made for periods 01, 02, and 03 have been fully offset against total normal tax liability 1 3.
Handle exceptions and unresolved cases: payment calendar
Edge cases and statutory adjustments
- Ceasing South African Tax Residence (Section 9H): If an individual ceases residence during an assessment year, the year of assessment ends on the date of departure, creating two separate assessment periods 5 55. The date of ceasing residence must be manually entered on the IRP6 return 5 56.
- SARS Justification Letters (Paragraph 19(3)): SARS may issue a Paragraph 19(3) engagement letter requiring justification of estimates 37 40 57. Supporting documentation must be uploaded on eFiling within 10 business days 57. If SARS is dissatisfied, the Commissioner may increase the estimate, an adjustment that is not subject to objection or appeal 37 40.
- Underestimation Penalties (Paragraph 20):
- Taxable Income ≤ R1 Million: A 20% penalty applies if the second period estimate is less than 90% of actual taxable income and also less than the basic amount 58.
- Taxable Income > R1 Million: A 20% penalty applies if the estimate is less than 80% of actual taxable income 59.
- Penalty Reduction: Paragraph 20 underestimation penalties are automatically reduced by any Paragraph 27 late payment penalty levied for the same period 59 60.
- Late Payment Penalty (Paragraph 27): A penalty of 10% is levied on any late payment of provisional tax for the first and second periods 61.
- Provisional Tax Deferral Exclusion: Instalment payment agreements under Section 167 of the Tax Administration Act apply solely to assessed tax debts; deferral of payment does not apply to provisional tax prior to formal assessment 62.
Next steps for Provisional tax
Task and completion checklist
| Step | Input or evidence | Responsible person | Completion check | Exception or next action |
|---|---|---|---|---|
| 1. Confirm Status | Income streams, IRP5s, interest certificates 25 30 | Taxpayer / Evolv Advisor | Non-remuneration income exceeds R30 000 threshold 25 32 | Excluded if taxable income is below annual tax threshold 32 33 |
| 2. Retrieve Basic Amount | Latest SARS Notice of Assessment (ITA34) 23 24 | Tax Compliance Officer | Assessment issued ≥ 14 days prior to submission 23 24 | Apply 8% annual uplift if notice is >18 months old 39 40 |
| 3. Request IRP6 | Active eFiling profile login 7 22 | Evolv eFiler | Select period (e.g., 2027-01) on eFiling dashboard 44 46 | Register provisional tax product on eFiling if unlisted 7 |
| 4. Calculate Estimate | Income schedules, PAYE, medical tax credits 27 29 | Tax Practitioner | Net tax liability verified against current individual rates 15 27 | Upload 10-day justification records if flagged under Para 19(3) 57 |
| 5. File Return | Completed eFiling IRP6 form 26 45 | Taxpayer / Agent | Work Page status reflects "Filed through eFiling" 45 46 | Correct period errors via "Request for Correction" function 54 |
| 6. Execute Payment | 19-digit PRN, bank beneficiary ID 50 52 | Finance Lead / Individual | Bank debit confirmation matching IRP6 amount due 50 52 | Pay prior to last business day if deadline falls on weekend 9 10 |
| 7. Audit Account | Provisional Tax Statement of Account (PTAX SOA) 53 54 | Tax Compliance Lead | Zero balance or valid credit on PTAX statement 54 | Settle top-up by 30 September to mitigate 89quat interest 9 12 |
Frequently Asked Questions
What happens if my provisional tax return calculation results in a nil payment?
You are legally required to request and submit an IRP6 return for both first and second periods even if the tax calculation results in a nil (R0.00) payment 36 63. Failure to submit timeously results in SARS deeming an estimate of nil taxable income, exposing you to underestimation penalties upon final assessment 64 65.
Can I apply for a Section 167 instalment payment agreement to defer provisional tax?
No. Section 167 of the Tax Administration Act applies exclusively to outstanding tax debts arising from issued assessments 62. It cannot be utilized to defer biannual provisional tax payments prior to assessment 62.
How is the basic amount updated if my last assessment was issued over 18 months ago?
If your latest preceding tax assessment was issued more than 18 months prior to submitting your IRP6 estimate, the basic amount (assessed taxable income less capital gains and lump sums) must be automatically increased by 8% per annum 23 39 40.
What is the deadline for making an optional third provisional tax payment?
For individual taxpayers with a February tax year-end, the voluntary third (top-up) payment must be settled no later than the last business day of September following the end of the tax year 9 12.
Are directors of private companies automatically treated as provisional taxpayers?
No. Directors of private companies and members of close corporations are classified as employees for PAYE purposes and are not automatically provisional taxpayers unless they earn independent income outside their standard remuneration 35 36.
Related guides
- Who is a provisional taxpayer in South Africa
- Calculating a first provisional tax payment
- The Proactive SARS Audit Guide: Keeping Your Business Ledger Sanitised
Sources
- https://www.sars.gov.za/wp-content/uploads/Ops/Guides/GEN-PT-01-G01-Guide-for-Provisional-Tax-External-Guide.pdf
- Provisional Tax | South African Revenue Service
- Rates of Tax for Individuals | South African Revenue Service
- Companies, Trusts and Small Business Corporations (SBC) | South African Revenue Service
- https://www.sars.gov.za/wp-content/uploads/Ops/Guides/GEN-PT-01-G02-How-to-eFile-your-Provisional-Tax-Return-External-Guide.pdf