
Resolving an expired letter of good standing
4 May 2026
An expired Letter of Good Standing requires a current replacement from the Compensation Fund. Check outstanding returns, assessments and payments before requesting it.
An expired Compensation Fund Letter of Good Standing needs a current replacement.
Check the actual account for outstanding returns, unpaid assessments, unallocated payments or audit queries and resolve any items found.
A Letter of Good Standing has its own stated validity dates. An expired letter does not itself prove unpaid assessments, missing returns or an audit block. Check the certificate’s expiry date and the employer’s Fund statement and filing history, address actual outstanding items, then request a current letter. Compensation Fund guidance.
Missing returns balances and expired status
This technical draft applies to South African SME employers, financial directors, and payroll administrators operating within the jurisdiction of the Republic of South Africa under the administration of the Compensation Commissioner and the Department of Employment and Labour Compensation Fund 9 10. Use the earnings period specified for the actual employer return; do not confuse it with the Fund’s own financial year 3 11.
Full task completion requires more than generating an online submission confirmation; it requires zeroing all outstanding assessment balances, clearing any audit flags, and successfully downloading a valid, verified Letter of Good Standing 1 2 12.
To maintain clarity, employers must distinguish between statutory law, regulator guidance, and Evolv recommendations:
— Practical point from this guide
- Statutory Law: Established primarily under the Compensation for Occupational Injuries and Diseases Act 130 of 1993 (COIDA) 13 and the Compensation for Occupational Injuries and Diseases Amendment Act 10 of 2022 14. The law mandates annual returns 4, empowers the Commissioner to issue estimated assessments and levy penalties for late or false returns 15 16 17, and enforces joint financial liability for principal contractors who engage non-compliant sub-contractors 18 19.
- Regulator Guidance: Operational instructions and user guides issued by the Department of Employment and Labour 12 20. Guidance dictates online portal navigation steps 21, mandatory 99-prefixed deposit reference formatting 2 6, and specific email channels for unallocated payment queries and audit clearance 2 5.
- Evolv Recommendations: Advisory standards provided by Evolv Accountants across bookkeeping, accounting, tax advisory, payroll, and statutory compliance. Evolv recommends conducting rigorous pre-submission reconciliations against SARS EMP501 filings, retaining supporting schedules for five years, and securing written confirmation of unallocated payment allocation before reapplying for a Letter of Good Standing.
Prepare the information and authority: missing returns balances
Before attempting to resolve an expired status online, the employer or authorised representative must compile primary documentation, establish legal authority, and calculate reportable employee earnings 3 5 22.
Required Primary Documents and Authority
- SARS EMP501 Employer Reconciliations: Annual employer reconciliation declarations filed with SARS, accompanied by a Tax Clearance certificate if exempt from Skills Development Levy 5 22.
- UIF Registration Proof: Formal confirmation of active registration with the Unemployment Insurance Fund 5.
- Detailed Payroll Reports: Itemised payroll summaries breaking down personnel salaries, wages, director remuneration, and allowances for each missing assessment year 5 22.
- Annual Financial Statements: Audited, independently reviewed, or compiled Annual Financial Statements covering all outstanding financial years 5 22.
- Sworn Affidavits and Signed Manual WAS.8 Forms: A sworn affidavit detailing true earnings figures accompanied by a completed, signed manual Return of Earnings (WAS.8) form 5 22.
- Power of Attorney: A formal Power of Attorney document signed by company leadership when an accounting practitioner or payroll consultant represents the employer 5 22.
Statutory Definitions and Inputs
- Reportable earnings: Use the earnings definition and annual ceiling applicable to the declared period, and the return’s requested breakdown. The Fourth Schedule alignment in section 1(g) of Act 10 of 2022 is listed as awaiting commencement on the official Act page, so do not apply it merely because it appears in the 2022 amendment. Official commencement schedule.
- Director Remuneration: Remuneration of a director of a legal person who meets the amended employee definition, including the applicable contract-of-employment, apprenticeship or learnership relationship 25 26. Director earnings must be declared separately from general employee earnings during portal submission 7.
- Record retention period: Keep the section 81 earnings register and supporting prescribed particulars for at least five years after the last entry. This is the commenced rule; do not treat the older four-year manual as an alternative current minimum. Amended section 81; Commencement dates.
Complete the task step by step: expired status
Follow this primary sequence to submit outstanding returns, settle balances, and retrieve a Letter of Good Standing:
- Access the Online Portal: Navigate to the Department of Employment and Labour ROE online platform (https://cfonline.labour.gov.za/OnlineSubmissions) or user login page 12 28. Enter the registered user credentials 28.
- Verify Contract Account Registration: Under Application for ROE Form, enter the organisation's Compensation Fund registration number, which is a Contract Account number starting with 99 6. Click Get Organisation to load organisation details 6.
- Navigate to Return Submission: Click on ROE Menu at the top left corner of the screen and select Submit Returns of Earnings 21. Select the missing assessment year from the drop-down menu 21.
- Capture Headcount and Payroll Totals: Tick the terms and conditions acceptance box 7. Input the exact number of employees, total employee earnings, and total director earnings for both the Final Assessment (actual earnings for the completed year) and Provisional Assessment (estimated earnings for the upcoming year) 7.
- Save and Confirm Values: Click Save Return of Earnings 7. A pop-up table titled Confirm the values will display the captured totals 7 8. Review these figures carefully. Clicking Yes submits the return 8. Once submitted, figures cannot be corrected online; any subsequent amendment requires a formal manual application for revision 8.
- Generate Notice of Assessment: Upon confirmation, the system updates the status to Completely processed and issues an online Notice of Assessment / Invoice 8. Note the invoiced amount, invoice number, due date, and deposit reference number 8.
- Execute Assessment Payment: Pay the invoiced assessment fee via direct deposit or electronic funds transfer (EFT) to the Compensation Fund's bank account 2 8. The deposit reference must be the 99-prefixed Contract Account number 2 8.
- Verify Allocation and Unblock Account: If the payment fails to allocate automatically, email proof of payment to Clarification@labour.gov.za 2. If the account is flagged with an audit block, submit supporting records to 2019ROE.Audits@labour.gov.za 5.
- Download Letter of Good Standing: Once all fees, penalties, and interest are fully settled, navigate to the portal menu to request and retrieve the official Letter of Good Standing 2 12.
Check the result against the evidence: missing returns balances
Submitting returns or uploading payment proofs does not guarantee that good standing has been achieved 1. Independent completion verification requires three distinct evidentiary checks:
- Zero Balance Account Statement: Obtain an updated account statement from the Fund (or via cfdebtors@labour.gov.za) confirming that all assessment fees, late submission penalties, and interest have been credited and that the outstanding balance is zero 2.
- Clearance of Audit Flags: Confirm that the portal status does not display Employers Blocked for Audit 1. If an audit block was raised, written confirmation must be obtained from the Compensation Fund audit section confirming that submitted payroll reports, SARS EMP501 filings, and financial statements have cleared the review 1 5.
- Valid Document Generation: Generate and download the PDF Letter of Good Standing directly from the ROE website 12. Verify that the document displays the correct employer registration name, contract account number, issue date, and expiry date.
Handle exceptions and unresolved cases: expired status
Audit Blocks and Incorrect Submissions
If an employer submits incorrect earnings figures or triggers automated system audit thresholds, the account will reflect Employers Blocked for Audit, preventing online generation of a Letter of Good Standing 1 22. To unblock the account, the employer must submit:
- A sworn affidavit explaining the variance and confirming correct earnings 5 22.
- A signed manual Return of Earnings (WAS.8) form 22.
- SARS EMP501 employer reconciliations or Tax Clearance certificate 5 22.
- Detailed payroll reports and Annual Financial Statements 5 22.
- Power of Attorney if represented by a consultant or accountant 5 22.
Submit these documents directly to 2019ROE.Audits@labour.gov.za 5. If primary financial records are unavailable, the employer may submit an estimation request on company letterhead accompanied by a sworn affidavit 29.
Revision of Assessment
Where an employer identifies an error on a submitted declaration, a formal application for revision of assessment must be submitted within 30 calendar days from the date of the Notice of Assessment 30. The application must be supported by the full audit clearance document set 18.
Unallocated Payments
Payments made using an incorrect reference or affected by banking system errors will leave assessment balances unpaid 2. Employers must submit bank proof of payment showing the correct 99-prefixed Contract Account number to Clarification@labour.gov.za 2.
Ceased, Liquidated, or Restructured Entities
Employers whose businesses have closed, ceased trading, changed their nature of business, or entered liquidation must not submit Return of Earnings online 22. Formal manual notification and deregistration applications (Form CF 1C) must be submitted to the Fund 22 31.
Subcontractor Liabilities
Principal contractors (principal contractors) who engage sub-contractors must ensure that every sub-contractor holds a valid Letter of Good Standing 18 19. Under Section 89 of COIDA, if a sub-contractor fails to register or pay assessments, the principal contractor becomes liable for compensation claims and outstanding assessments 18 19. Assessment amounts paid by a principal contractor on behalf of a sub-contractor may be set off against debts owed to that sub-contractor 19.
Next steps for COIDA and compensation
Reusable Action Checklist
- Verify online portal access and confirm the 99-prefixed Contract Account number 6 12.
- Extract payroll reports, director remuneration schedules, and SARS EMP501 filings for all outstanding assessment years 3 5 22.
- Capture final actual earnings and provisional estimated earnings on the ROE website 7.
- Confirm submitted figures and obtain the online Notice of Assessment / Invoice 7 8.
- Execute EFT payment using the 99-prefixed Contract Account reference 2 8.
- Clear unallocated payment queries (Clarification@labour.gov.za) or audit blocks (2019ROE.Audits@labour.gov.za) if flagged 2 5.
- Download the official Letter of Good Standing 2 12.
Reproducible Hypothetical Example
Note: All values in this scenario are illustrative model inputs to demonstrate assessment mechanics.
An SME employer in South Africa failed to submit its Return of Earnings for the preceding assessment year. The employer's payroll records reflect the following actual figures:
- Number of employees: 10
- Actual employee earnings: R1 000 000
- Director earnings: R200 000
- Total actual reportable earnings: R1 200 000
- Applicable assessment rate (illustrative): 1.5% (R1.50 per R100 earnings)
Calculation Sequence:
- Basic Assessment: R1 200 000 × 1.5% = R18 000.
- Late Submission Penalty: Assume the Fund made an estimated assessment of R18,000 under section 83(6) and imposed the 10% penalty on that assessed amount under section 83(6)(b) 16 17 32:
Penalty = R18 000 × 10% = R1 800
- Total Invoiced Amount: R18 000 (Assessment) + R1 800 (Penalty) = R19 800.
- Payment Execution: The employer executes an EFT of R19 800 using deposit reference 990000123456 (Contract Account number) 2 8.
- Completion Check: Upon settlement, the system account balance reflects zero, after which the employer checks allocation and resolves any audit or other outstanding requirements before retrieving the letter 2 12.
Task and Completion Checklist
Artefact: Task and completion checklist; columns: Step | Input or evidence | Responsible person | Completion check | Exception or next action
| Step | Input or evidence | Suggested owner | Completion check | Next action |
|---|---|---|---|---|
| Identify the issue | Expired letter, account statement and filing history | Employer | Actual missing returns, unpaid items or queries identified | Do not infer a debt solely from certificate expiry |
| Correct returns | Actual-period payroll, ROE and required supporting records | Authorised representative | Correct return or revision request submitted and result retained | Follow the applicable administrative revision route for a processed error |
| Settle or query amounts | Current assessment and payment evidence | Finance manager | Correct account and period credited | Use the published payment-allocation query route for unmatched cash |
| Address an audit query | Issuer’s request and authorised supporting documents | Employer or appointed representative | Record the Fund’s decision or outstanding requirements | Follow the current case instructions; do not assume an automatic unblock |
| Request replacement | LOGS facility and actual account standing | Authorised representative | Current letter retrieved and verified for the required period | Follow up remaining issuer queries |
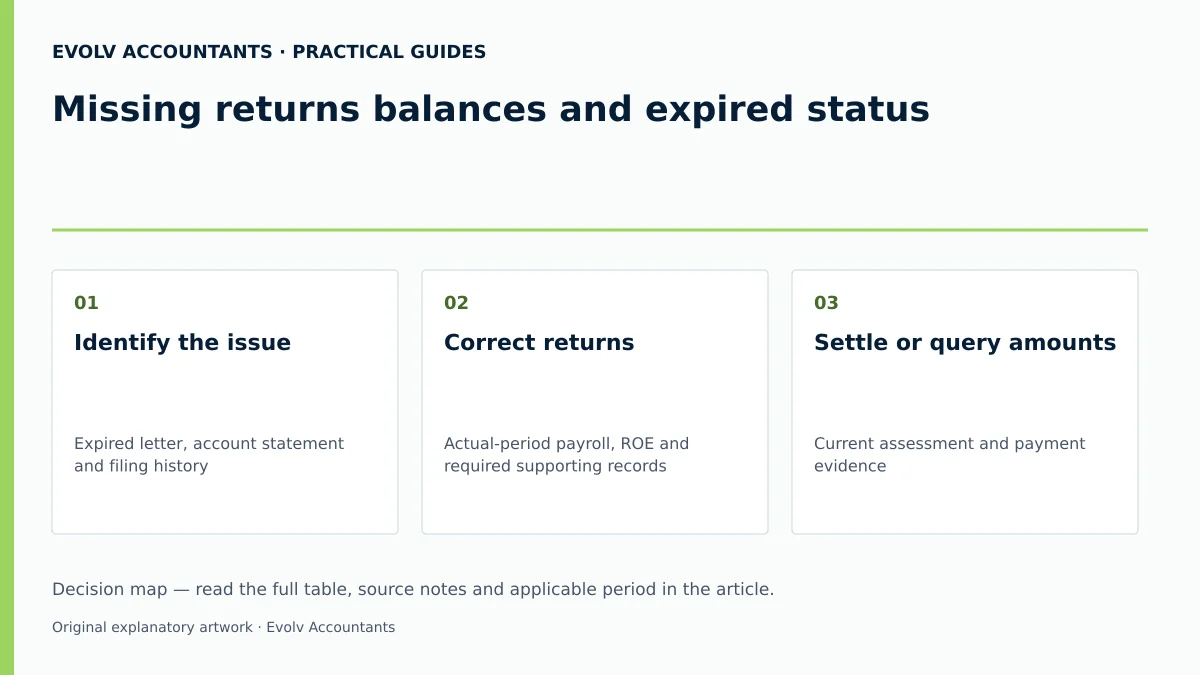
Official guidance; Official guidance.
Frequently Asked Questions
Does an expired letter prove that returns or assessments are outstanding?
An expired letter needs replacement for the period required by the recipient. Missing annual returns can prevent the Fund from assessing the account and can obstruct issue of a current letter, but expiry alone does not diagnose the underlying cause. Check the return history, account and audit status. Fund guidance.
What penalties and interest are charged for outstanding COIDA assessments?
Missing returns can result in estimated earnings and an assessment, with section 83(6) specifying penalties on the assessed amount and, in relevant cases, the assessment difference. Non-payment penalties under section 87 use distinct statutory bases, and overdue amounts can attract interest. Check the actual notice, applicable provision and period rather than applying one universal10% formula. Amended COIDA penalty provisions.
How long must an SME retain payroll and wage records for COIDA audit compliance?
Under Section 81(2) of COIDA Act 130 of 1993, employers are legally required to retain wage registers and payroll records for at least five years 4. Section 50 of Amendment Act 10 of 2022 extends this retention obligation to five years 27. Amended COIDA section 81; 2026 commencement dates.
What should an SME do if its portal account is flagged with an audit block?
When an account reflects Employers Blocked for Audit, the employer must compile a signed manual Return of Earnings (WAS.8), a sworn affidavit, SARS EMP501 filings, detailed payroll reports, Annual Financial Statements, and a Power of Attorney (if represented), and email the document set to 2019ROE.Audits@labour.gov.za 1 5 22.
Is a principal contractor liable if a subcontractor operates with an expired Letter of Good Standing?
Yes. Under Section 89 of COIDA, a principal contractor who engages a sub-contractor is legally obligated to ensure the sub-contractor is registered and up to date with assessment payments 18 19. If the sub-contractor fails to pay assessments or register, the principal contractor becomes liable for outstanding assessments and employee compensation claims arising from that work 18 19. Ask Evolv about missing returns balances and expired status. Share the relevant records so the support required can be scoped.
Related guides
- Correcting a return of earnings submitted incorrectly
- When an employer must register with the Compensation Fund
- Compliance and Regulations: Keeping Your Business on Track
Sources
- Compensation Fund: obligations of the employer
- Compensation for Occupational Injuries and Diseases Act 130 of 1993 — original Act
- https://www.labour.gov.za/DocumentCenter/Publications/Compensation%20for%20Occupational%20Injuries%20and%20Diseases/Return%20of%20Earnings%20User%20Manual%2C%20August%202019.pdf
- How To Submit Earnings Statements to the Compensation Fund
- https://www.gov.za/sites/default/files/gcis_document/202304/48431-17-4-compensationoccupinjuriesdiseasesamendact10of2022a.pdf
- Compensation for Occupational Injuries and Diseases Amendment Act 10 of 2022 (English / Afrikaans) | South African Government