
UIF contributions when a business closes
30 June 2026
Closing a South African business requires finalising employee UIF declarations and settling outstanding contributions within statutory deadlines.
On closure, submit final employee declarations and actual termination reasons to the UI Commissioner and settle contributions through the applicable collecting authority. Where the employer is registered with SARS, final monthly EMP201 duties and the final EMP501 are separate: the reconciliation is due within 14 days of ceasing business unless SARS allows a longer period. Retain the filing result and follow the applicable cancellation process.
Final employee declarations and closure confirmation
This guidance is tailored for directors, owners, liquidators, and financial managers of South African Small and Medium Enterprises (SMEs) operating within the legal jurisdiction of the Republic of South Africa 1 2. The relevant compliance period covers the final trading month and the applicable tax year up to the exact date on which the business officially ceases to employ staff or carry on trade 3 4.
Achieving full legal completion of UIF duties upon business closure does not occur automatically upon commercial shutdown. Completion specifically means that:
- All monthly employee employment and remuneration records up to the final date of service have been uploaded to the Unemployment Insurance Commissioner's database 5 6.
- The final 2% monthly contribution payment (comprising 1% deducted from employees and 1% contributed by the employer) has been submitted to SARS with a pre-populated Payment Reference Number (PRN) within the statutory 7-day payment window 7 8 9.
- An final Employer Reconciliation Declaration (EMP501) reconciling all EMP201 monthly declarations against issued tax certificates has been lodged within 14 days of ceasing to be an employer 4 10.
- Formal written notification of registration cancellation (using form EMP123) has been served on SARS within 14 days of business cessation 3 11.
Distinguishing between regulatory bodies is critical: while SARS collects financial contributions for employers registered for Pay-As-You-Earn (PAYE) or Skills Development Levy (SDL), the UI Commissioner maintains the employee database 12 13 14. Therefore, employee status declarations (such as termination details) must always be submitted directly to the UI Commissioner regardless of where financial contributions are paid 6.
Prepare the information and authority: final employee declarations
Statutory authority and representative employer obligations
In terms of the Income Tax Act Fourth Schedule and the Unemployment Insurance Contributions Act (UIC Act), when a company enters liquidation or closes, the legal obligation to complete tax and UIF duties falls upon the designated representative employer 15 16. In the case of a company under liquidation, this role transfers to the appointed liquidator or judicial manager; for an operating company, it rests with the public officer, director, or secretary 17.
The representative employer remains personally liable for duties imposed on the employer under the Tax Administration Act (TA Act) 17 18.
Required documentation and data inputs
Before initiating final declarations and deregistration, the representative employer must assemble the following primary records:
— Practical point from this guide
- Employee Master Data: Full legal names, South African identity numbers or valid passport numbers, residential and postal addresses, and banking details 19 20 21.
- Employment Termination Records: Exact date of employment commencement, final termination date, and the specific termination reason code (e.g. commercial closure or redundancy) 20 22.
- Payroll and Remuneration Registers: Monthly gross earnings and calculated UIF-deductible remuneration for each employee covering all un-reconciled months of the tax year 20 21.
- Historical Submission Records: Previous EMP201 monthly payment declarations, eFiling PRN receipts, and proof of payment for the preceding 5 years 9 23 24.
Remuneration definitions, rates, and statutory thresholds
Under Section 1 of the UIC Act, remuneration for UIF calculation purposes includes regular gross salary and wages, but explicitly excludes the following statutory items 16 25:
- Retirement or superannuation allowances and pensions 16 25.
- Statutory lump sum payments contemplated in gross income definitions (such as severance or retirement lump sums) 16 25.
- Amounts paid by way of commission 16 25.
- Remuneration paid to employees who work for the employer for less than 24 hours in a calendar month 26 27.
The statutory contribution rate mandated by Section 6 of the UIC Act is exactly 2% of deductible remuneration, split equally 7 28 29:
- Employee Contribution: 1% deducted monthly from the employee's remuneration by the employer 7 28 30.
- Employer Contribution: 1% contributed directly by the employer 7 28.
All calculations are subject to the statutory monthly earnings ceiling determined by the Minister of Finance 29 31. Effective from 1 June 2021, the maximum earnings ceiling for UIF contribution calculations is R17,712 per month (or R212,544 annually) 7 23 31. For any employee earning above R17,712 per month, the maximum monthly contribution is capped at R177.12 from the employee and R177.12 from the employer, resulting in a maximum total monthly contribution of R354.24 per employee 23.
Earnings above R17,712 per month are excluded from remuneration for UIF purposes 23.
Complete the task step by step: closure confirmation
Executing a compliant closure of employer UIF obligations requires completing five sequential steps grounded in SARS and Department of Employment and Labour instructions 3 4 5 9:
Step 1: Submit final employee status updates to the UI Commissioner
Before closing payroll software or deregistering accounts, the employer must update each employee's record on the UI Commissioner's database 5 6. Using uFiling (or prescribed electronic payroll files), navigate to the Declarations Manager, edit each employee profile to capture their final termination date and closure reason, and submit the monthly UI-19 declaration 5 6 22 32. This step ensures the worker database reflects active employment cessation so former staff can lodge valid benefit claims 1 5 33.
Step 2: Calculate final monthly payroll deductions and employer liability
Process the final payroll run up to the last working day. Apply the 1% employee deduction and 1% employer contribution to each employee's qualifying remuneration, enforcing the R17,712 monthly earnings cap per individual 7 23 31. Confirm that no arrear deductions from prior financial years are being deducted from employees, as prohibited by Section 7 of the UIC Act 34.
Step 3: Lodge the final EMP201 and settle contributions with SARS
Within seven days following the end of the final trading month, request and submit the Monthly Employer Declaration (EMP201) via SARS eFiling or e@syFile 9 23 34. If the 7th day falls on a weekend or public holiday, payment and submission must occur on the last business day prior 8 34. Remit the total 2% contribution amount using the pre-populated 19-digit Payment Reference Number (PRN) via approved bank EFT channels or eFiling credit push 8 9 23.
Step 4: Render the final Employer Reconciliation Declaration (EMP501)
In accordance with Paragraph 14(3) of the Fourth Schedule, an employer who ceases to carry on business or ceases to be an employer must submit an Employer Reconciliation Declaration (EMP501) within 14 days after the date of cessation 4. Generate IRP5/IT3(a) tax certificates for all employees covering the shortened final tax period, reconcile the total UIF deductions on certificates against monthly EMP201 declarations paid, and submit the reconciliation statement to SARS 4 10.
Step 5: Submit formal written deregistration (Form EMP123) to SARS
Under Paragraph 15(3) of the Fourth Schedule and Section 8(2A) of the UIC Act, the employer must notify the SARS Commissioner in writing within 14 days of ceasing to be an employer 3. Submit Form EMP123 (Application for Cancellation of Registration of a Person in respect of All His Business) to SARS to officially close the PAYE, SDL, and UIF tax profiles 3 11.
Check the result against the evidence: final employee declarations
The representative employer must verify completion through independent statutory evidence rather than assuming digital submission guarantees acceptance 10 35:
- UI Commissioner Database Verification: Log into uFiling, select the employer profile under Declarations Manager, and navigate to "View Returns" or "Calculate Returns" 32 35. Verify that the status for the final declaration period displays as "Submitted" or "Accepted" 35 36. Check individual employee status screens to confirm termination dates and reasons are logged 22 32.
- SARS Payment Matching: Access SARS eFiling and inspect the Employer Statement of Account. Confirm that the final payment made using the 19-digit PRN has been allocated against the EMP201 liability and that the UIF account reflects a zero balance owing 9 23.
- EMP501 Reconciliation Acceptance: Obtain the official SARS EMP501 final acceptance letter. Verify that all IRP5/IT3(a) certificates issued match the monthly totals declared and that no reconciliation discrepancies (EMP501 vs EMP201 differences) remain 4 10.
- SARS Deregistration Confirmation: Ensure SARS issues written confirmation that employer tax numbers (PAYE/SDL/UIF) have been cancelled following receipt of Form EMP123 3 11.
- Statutory Record Retention Archive: Store all final payroll registers, proof of payment, employee ID copies, and declaration acceptance receipts in a secure archive. Under Chapter 4 of the TA Act and Paragraph 14(1) of the Fourth Schedule, these records must be retained and made available for inspection for 5 years from the return submission date 21 24.
Handle exceptions and unresolved cases: closure confirmation
Vetting failures or blocked portal access on uFiling
When managing closure declarations on uFiling, users undergoing account updates or initial registration may encounter a "Vetting Failed" status if demographic or address details do not match Department of Employment and Labour records 37 38. In such instances, the portal account is suspended 37. If vetting fails, follow the portal prompt to contact uFiling Support through “UIF Services Support”.
Send identity documents only through the route and with the safeguards specified by the support team. uFiling user guide.
Insolvency and liquidator transition
When a SME ceases operating due to liquidation, existing directors lose legal authority to manage payroll affairs. Under the Fourth Schedule, the liquidator assumes the role of representative employer 17. The liquidator must furnish written notice to SARS, lodge final returns up to the date of liquidation, and settle outstanding obligations from estate assets 3 17.
Handling arrears, 10% penalties, and interest
If a closing business has outstanding prior-period UIF liabilities, statutory penalties and interest will apply:
- Default Penalty: A mandatory penalty of 10% is imposed under Section 13 of the UIC Act on any contribution remaining unpaid after the statutory due date 39.
- Statutory Interest: Interest accrues under Section 12 of the UIC Act at the prescribed rate from the day following the due date until full payment is received by SARS or the UI Commissioner 39 40.
- Estimated Assessments: If an employer fails to submit final returns, SARS may issue an estimated assessment under Chapter 8 of the TA Act 41. The employer remains liable for estimated amounts until formal returns, objections, or appeals are resolved 41 42.
Failure to submit required returns or pay withheld contributions constitutes a criminal offence under Chapter 17 of the TA Act, punishable upon conviction by a fine or imprisonment for up to two years 43 44 45 46. Evolv Accountants recommends conducting an immediate compliance audit of historical declarations prior to submitting closure forms to resolve missing periods proactively.
Next steps for UIF employer duties
To ensure systematic compliance during business closure, representative employers should follow the structured checklist below:
| Step | Input or evidence | Responsible person | Completion check | Exception or next action |
|---|---|---|---|---|
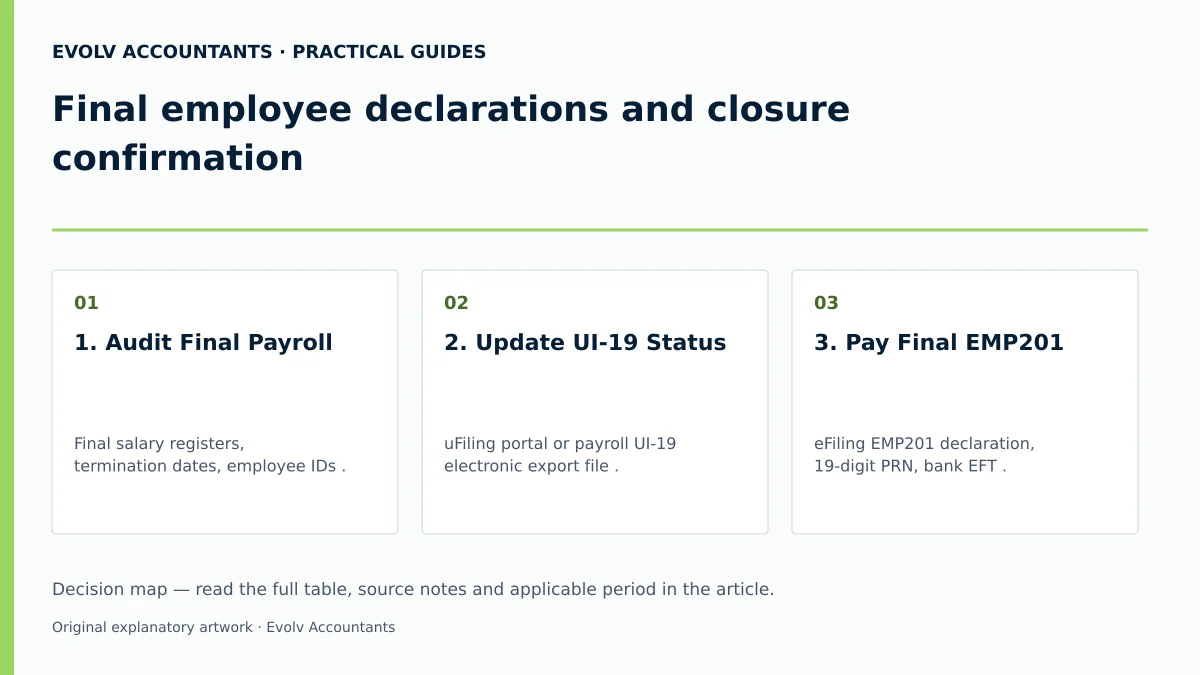
| 1. Audit Final Payroll | Final salary registers, termination dates, employee IDs 20 21. | Payroll Administrator / Director | All staff termination reasons and final gross pay verified 20 22. | Resolve missing employee ID/passport numbers prior to declaration 20. |
| 2. Update UI-19 Status | uFiling portal or payroll UI-19 electronic export file 5 6. | Representative Employer / Practitioner | Declaration confirmation retained and status shows "Submitted" 35. | Resolve vetting failures via uFiling Support email if blocked 37 38. |
| 3. Pay Final EMP201 | eFiling EMP201 declaration, 19-digit PRN, bank EFT 8 9 23. | Financial Manager / Director | Where SARS collection applies, check payment by the seventh calendar day after month-end and allocation to the final period 8 9 34. | Pay before weekend/holiday if 7th falls on non-business day 8 34. |
| 4. File Final EMP501 | e@syFile / eFiling EMP501 return, IRP5/IT3(a) certificates 4 10. | Tax Practitioner / Liquidator | Final EMP501 lodged within 14 days of cessation, unless SARS allows a longer period; retain the submission result 3 4. | Correct certificate discrepancies if EMP501 balancing fails 10. |
| 5. Deregister Profile | Form EMP123 submitted in writing to SARS 3 11. | Representative Employer / Public Officer | Written deregistration confirmation issued by SARS 3 11. | Follow up on an unresolved cancellation request through SARS; retain its reference 3 47. |
| 6. Archive Records | Complete digital & paper file of declarations and receipts 21 24. | Company Secretary / Representative | Files securely archived for statutory 5-year period 21 24. | Ensure electronic backups are readable and accessible for inspection 21 24. |
Reproducible hypothetical calculation example
Consider an SME closing operations on 15 November 2026 with three employees on its final payroll run:
- Employee A: Earns a final monthly remuneration of R12,000.
- Employee B: Earns a final monthly remuneration of R17,712.
- Employee C: Earns a final monthly remuneration of R25,000 (exceeding the statutory ceiling).
Statutory Thresholds & Rates Applied:
- Contribution rate: 1% employee deduction + 1% employer contribution = 2% total 7 28 29.
- Maximum monthly earnings ceiling (effective 1 June 2021): R17,712 per month 7 23 31.
Calculation Breakdown:
- Employee A (R12,000 remuneration):
- Employee deduction (1%): R12,000 × 1% = R120.00 7 28.
- Employer contribution (1%): R12,000 × 1% = R120.00 7 28.
- Total monthly UIF contribution: R240.00 7 29.
- Employee B (R17,712 remuneration):
- Employee deduction (1%): R17,712 × 1% = R177.12 7 23.
- Employer contribution (1%): R17,712 × 1% = R177.12 7 23.
- Total monthly UIF contribution: R354.24 7 23.
- Employee C (R25,000 remuneration - Capped at R17,712):
- Subject remuneration is capped at R17,712 (the R7,288 excess is excluded from UIF) 23 31.
- Employee deduction (1%): R17,712 × 1% = R177.12 23.
- Employer contribution (1%): R17,712 × 1% = R177.12 23.
- Total monthly UIF contribution: R354.24 23.
Total Final EMP201 UIF Payment to SARS:
- Total Employee Deductions: R120.00 + R177.12 + R177.12 = R474.24 7 23.
- Total Employer Contributions: R120.00 + R177.12 + R177.12 = R474.24 7 23.
- Combined Payment Remitted to SARS: R948.48 7 23 29.
Frequently Asked Questions
Do I submit employee termination details to SARS or the UI Commissioner when closing?
Employee employment status details (UI-19 forms) must be submitted directly to the UI Commissioner (via uFiling or payroll file upload) 6. SARS receives monthly financial contribution declarations (EMP201) and tax reconciliations (EMP501), but does not maintain the employee benefit database 6 10 12 14.
What is the deadline for filing the final EMP501 reconciliation when a business closes?
Under Paragraph 14(3) of the Fourth Schedule to the Income Tax Act, an employer who ceases to carry on business or ceases to be an employer must render the final EMP501 reconciliation return within 14 days after the date of cessation 4.
What happens if the 7th day of the month falls on a Sunday when paying the final EMP201?
If the statutory 7th-day deadline falls on a Saturday, Sunday, or public holiday, Section 9 of the UIC Act guidelines specify that payment must be received by SARS on the last business day prior to the weekend or public holiday 8 34.
Can an employer deduct arrear UIF contributions from employees upon closing down?
No. Under Section 7 of the UIC Act, an employer is strictly prohibited from deducting arrear contributions from an employee after the end of the financial year during which the contributions were payable 34. Arrear liabilities must be absorbed by the employer.
How long must payroll and UIF records be kept after a business has deregistered?
Under Chapter 4 of the Tax Administration Act and Paragraph 14(1) of the Fourth Schedule, all employee remuneration registers, contribution details, and filing receipts must be retained for a period of 5 years from the date of return submission 21 24. Ask Evolv about final employee declarations and closure confirmation. Share the relevant records so the support required can be scoped.
Related guides
- Correcting an employee UIF employment history
- When a small business must register for UIF
- Compliance and Regulations: Keeping Your Business on Track
Sources
- Unemployment Insurance Fund | South African Revenue Service
- https://www.sars.gov.za/wp-content/uploads/Ops/Guides/UIF-GEN-01-G01-Guide-for-Employers-in-respect-of-the-Unemployment-Insurance-Fund-External-Guide.pdf
- https://www.labour.gov.za/DocumentCenter/Publications/Unemployment%20Insurance%20Fund/uFiling%20System%20User%20Guide.pdf