
UIF obligations for domestic workers
26 February 2025
Complying with South African UIF obligations for domestic workers requires employers to register, deduct contributions, and maintain accurate monthly worker records with the UI Commissioner.
Under the Unemployment Insurance Act 63 of 2001 (UI Act) 1 and Unemployment Insurance Contributions Act 4 of 2002 (UIC Act) 1, employers hiring a domestic worker for 24 hours or more monthly must register and pay Unemployment Insurance Fund (UIF) contributions 2 3. The mandatory contribution rate is 2% of UIF remuneration after statutory exclusions, split as 1% deducted from the employee and 1% contributed by the employer 4 5.
As SARS Guide UIF-GEN-01-G01 states, "The employer must pay a total contribution of 2% (1% contributed by the employee and 1% contributed by the employer)" 4 6. Contributions are capped at R17,712 monthly (R212,544 annually) effective 1 June 2021 4 7 8, limiting maximum monthly contributions to R177.12 per party (R354.24 total) 7. Declarations and payments are due by the 7th day of each following month 9 10 11.
While contribution payments go to SARS or the UI Commissioner based on PAYE or SDL liability, including voluntary SARS employer registration 12 13 14, worker declarations must be submitted directly to the UI Commissioner 15 16.
Domestic employer registration and worker records
This guide assists South African SMEs, property managers, and household employers hiring domestic workers—such as cleaners, gardeners, nannies, and drivers 1 17—under statutory duties enforced by the Department of Employment and Labour alongside SARS 1 17 18.
Compliance is complete only when three conditions are met:
- Statutory Registration: Holding an active UI reference number with the UI Commissioner (and SARS if PAYE/SDL liable) 12 13 14.
- Worker Record Maintenance: Registering employee data—commencement dates, hours, remuneration, and beneficiaries—on the UIF database 10 19 20 21.
- Monthly Declarations and Payment: Submitting monthly worker declarations and paying the 2% contribution by the 7th of every month 6 9 10 11.
Compliance spans three levels:
- Statutory Law: The UI Act 1 and UIC Act 1 mandate registration, deductions, and penalties 16 22.
- Regulator Guidance: Rules in SARS Guide UIF-GEN-01-G01 13 23 and the uFiling Manual 10 govern submission channels.
- Evolv Recommendations: Controls advised by Evolv Accountants to ensure audit readiness and prevent account suspension.
Prepare the information and authority: domestic employer registration
Employers must assemble necessary demographic, employment, and authorisation inputs before registering.
Required Documents and Inputs
- Employer Details: SA ID/passport, full names, addresses, mobile, and email 24 25.
- Employee Details: Worker SA ID/foreign passport, full names, date of birth, addresses 19 24.
- Employment Inputs: Commencement date, monthly hours, gross remuneration, and job title 19.
- Beneficiary Details: Full names, ID numbers, and mobile numbers for at least one beneficiary (up to four) 20 26.
Legal Authority and Representation
Delegating domestic UIF declarations requires an authorised uFiling profile and the appropriate delegated permissions, such as Capture Declarations or Submit Declarations. SARS tax-practitioner mandates relate to SARS matters; use uFiling’s authority and delegation process for UIF declarations. uFiling delegation guidance.
Statutory Definitions
- Employee: A natural person receiving remuneration for domestic services, excluding independent contractors 10 30 and persons working under 24 hours monthly 2 3.
- Employer: Any person paying or liable to pay remuneration to a domestic worker 30.
- Remuneration for UIF: Start with remuneration as defined for the UIC Act and exclude commission, pensions, superannuation or retiring allowances, and the specified statutory gross-income lump sums. SARS UIF guide.
Complete the task step by step: worker records
Record management uses uFiling online workflows or manual Form UI-19 submissions 10 33.
Step 1: Account Registration and Vetting
- Access www.ufiling.co.za, select "REGISTER", accept terms, and enter contact details 24.
- Log in with temporary credentials, reset password, and complete demographic vetting 24 34.
Step 2: Registering the Domestic Employer
- Under "Registrations", select "Register" -> "Domestic Employer" 28 35.
- Confirm UI Act qualification criteria, capture employer details, and submit 25 28.
Step 3: Capturing Employee Declarations and Beneficiaries
- Under "Employee Declaration", enter worker ID, click "Retrieve", and verify details 19 25.
- Capture commencement date, monthly hours, and gross salary 19.
- Select "Add Beneficiary", input details, and save 20.
Step 4: Monthly Return and Contribution Payment
- Access "Declarations Manager", select employer profile, and review return 36 37.
- Confirm gross salary is capped at the R17,712 monthly ceiling 4 7 8.
- Submit declaration and pay 2% contribution via eFiling, EFT, or debit pull by 7th deadline 7 9 11.
Check the result against the evidence: domestic employer registration
Submission does not guarantee acceptance; independent completion evidence is required.
Primary Evidence Benchmarks
- UIF Reference Number: Issued via email upon registration 20.
- uFiling Return Status: Under "Declarations Manager", click "Calculate Returns". An accepted return displays "Submitted" 38 39.
- SARS Payment Confirmation: When paying via EMP201, payment requires a 19-digit Payment Reference Number (PRN) matched to a bank receipt 7 40.
- Active Employee Status: Under "Employment", verify the worker is listed as "Active" 37 41 42.
Reproducible hypothetical payroll calculation
Consider two domestic payroll scenarios.
Scenario A: Standard Wage Domestic Cleaner
A cleaner earns a gross monthly wage of R6,000 for 160 hours worked.
- Gross Remuneration: R6,000.00
- Employee Deduction (1%): R60.00
- Employer Contribution (1%): R60.00
- Total Monthly Contribution: R120.00
- Note: Full remuneration is subject to 2% as salary is below the ceiling.
Scenario B: High-Earning Household Manager
A household manager earns a gross monthly salary of R25,000.00.
- Gross Remuneration: R25,000.00
- Statutory Earnings Ceiling: R17,712.00 per month 4 7
- UIF Deductible Remuneration: R17,712.00
- Employee Deduction (1% of ceiling): R177.12 7
- Employer Contribution (1% of ceiling): R177.12 7
- Total Monthly Contribution: R354.24 7
- Note: Remuneration above R17,712 (R7,288.00) is exempt from UIF contributions 7.
Handle exceptions and unresolved cases: worker records
Specific procedures handle non-standard situations.
Vetting Failures on uFiling
Failing demographic vetting suspends the uFiling account 34. If vetting fails, follow the portal prompt to contact uFiling Support through “UIF Services Support”. Send identity documents only through the route and with the safeguards specified by the support team. uFiling user guide.
Foreign Workers and Foreign Passports
Foreign employees who meet the contribution rules must be included. If passport capture or verification fails, ask UIF Services Support to confirm the prescribed identification and submission route for the case; verify the current procedure before sending passport or work-permit copies. SARS UIF guide.
Bank Detail Modifications
For employer payment accounts, the uFiling guide describes “Add New” on the list of bank accounts, followed by “Update”. Its UI2.8 process concerns changes to the account holder’s own banking information: one portion is completed by the bank and another by the account holder. Use the workflow appropriate to the account being changed. uFiling banking guidance.
Workers Employed Under 24 Hours Per Month
Under Section 4(1)(b) of the UIC Act, employees working under 24 hours per month are exempt from UIF 2 3. Attendance records must be kept for 5 years to substantiate the exemption 46 47.
— Practical point from this guide
Next steps for UIF employer duties
Employers should execute the operational checklist below to maintain ongoing compliance.
| Step | Input or evidence | Suggested owner | Completion check | Exception or next action |
|---|---|---|---|---|
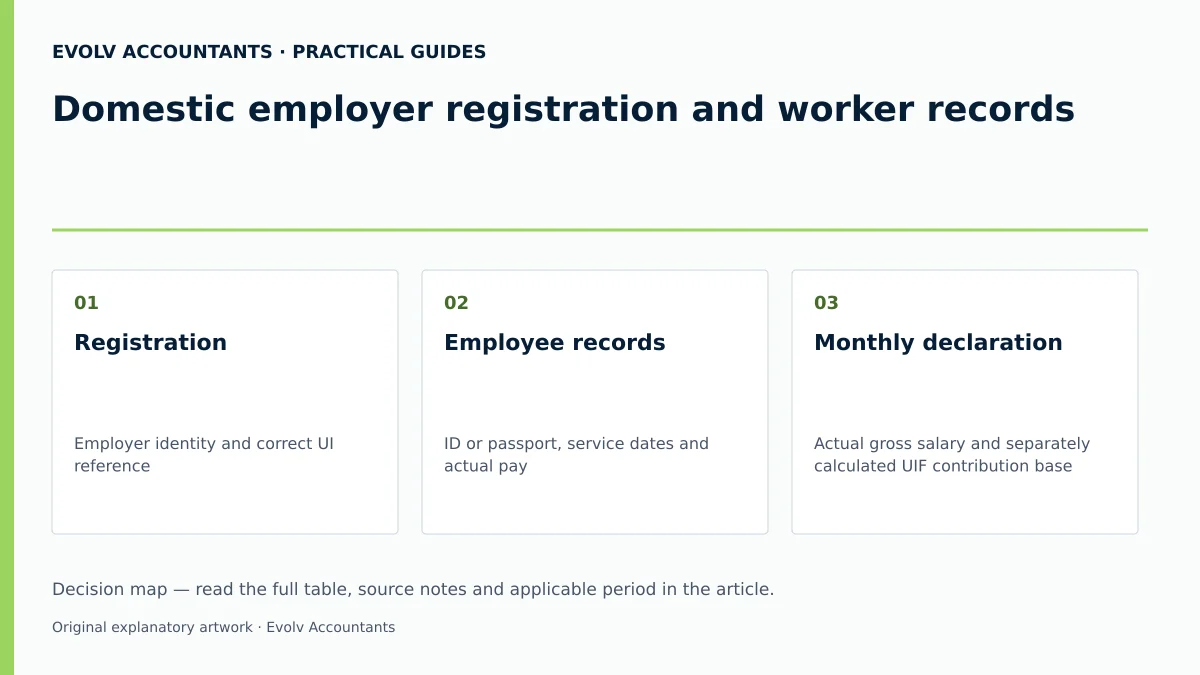
| Registration | Employer identity and correct UI reference | Employer or authorised delegate | Correct employer profile linked | Follow UIF Services Support instructions if vetting fails |
| Employee records | ID or passport, service dates and actual pay | Employer | Saved details agree with payroll evidence | Obtain the prescribed correction route if capture fails |
| Monthly declaration | Actual gross salary and separately calculated UIF contribution base | Payroll administrator | Submission confirmation and “Submitted” status retained | Correct master details and review the recalculated declaration |
| Contribution payment | 1% employee and 1% employer portions, subject to exclusions and ceiling | Employer | Payment credited to the correct authority and period | Pay SARS only where its collection rules apply; otherwise pay the UI Commissioner |
| Deadline and records | Applicable return, receipt and payment evidence | Employer | Due-date and retention checks completed | For SARS payments, the seventh moves to the preceding business day if necessary; retain records for the applicable period |
Official guidance; Official guidance; Official guidance.
Frequently Asked Questions
Are domestic workers working under 24 hours a month required to register for UIF?
No. Workers employed under 24 hours per month with a specific employer are exempt under the UIC Act exclusion for employment of fewer than 24 hours per month 2 3. Attendance records must be kept for 5 years 46 47.
How is UIF calculated if a domestic worker earns above the statutory ceiling?
Contributions are capped at the ceiling of R17,712 per month (R212,544 annually) 4 7 8. Maximum monthly contributions are R177.12 employee deduction and R177.12 employer contribution (R354.24 total) 7.
If an employer pays UIF to SARS via eFiling, must they still submit records to the UI Commissioner?
Yes. Paying via EMP201 does not fulfil worker declaration obligations 15 16. Worker declarations (UI-19 or uFiling) must be submitted directly to the UI Commissioner 15 16 33.
How do I change an employer payment account or my own banking details on uFiling?
For an employer payment account, the guide describes adding the account under “Add New” and saving it with “Update”. For changes to the user’s own banking information, follow the UI2.8 process, with one portion completed by the bank and the other by the user. uFiling banking instructions.
What penalties apply for late domestic UIF contributions?
Late payments incur a 10% default penalty under section 13 of the UIC Act and interest under section 12 48 49. Non-submission is an offence subject to fines or up to two years imprisonment 16 22 50 51.
Related guides
- Submitting monthly employee UIF declarations
- When a small business must register for UIF
- Compliance and Regulations: Keeping Your Business on Track
Sources
- Unemployment Insurance Fund | South African Revenue Service
- https://www.sars.gov.za/wp-content/uploads/Ops/Guides/UIF-GEN-01-G01-Guide-for-Employers-in-respect-of-the-Unemployment-Insurance-Fund-External-Guide.pdf
- https://www.labour.gov.za/DocumentCenter/Publications/Unemployment%20Insurance%20Fund/uFiling%20System%20User%20Guide.pdf
- Unemployment Insurance Fund