
VAT refunds after a change of bank details
18 October 2026
Updating bank details with SARS requires verifiable company records to ensure VAT refund readiness.
Vendors updating bank accounts must submit verified banking particulars through eFiling or in person at a SARS branch to maintain payment readiness 1. SARS pays valid Value-Added Tax (VAT) refunds within 21 business days of receiving a correctly completed VAT201 return, but changing banking particulars or submitting unverified data suspends payout until verified 2 3 4.
Verified bank details and payment readiness
Distinguishing change timelines in banking updates
When a South African small or medium enterprise (SME) alters its commercial banking partner, management must distinguish between four distinct timeline milestones to protect operational cash flow:
- Decision date: The date corporate management or the board formally resolves to open a new account or migrate banking operations 5 6.
- Effective date: The date the new bank account becomes operational for receiving operational revenues and paying commercial liabilities.
- Filing date: The date the vendor submits the bank detail change request to the South African Revenue Service (SARS) via eFiling or at a SARS branch 1.
- Reflected system change date: The date SARS completes verification and updates the core tax register, enabling refund disbursements into the new account 1 7.
Legal obligations versus administrative guidance
Under Section 21 of the Tax Administration Act and the VAT Act, a vendor must advise SARS in writing within 21 business days of any change in registered particulars, including banking details, business address, or representative vendor 8 9.
Regarding registration thresholds, Section 23 of the VAT Act sets a compulsory VAT registration threshold of R1 million in taxable supplies across any consecutive 12-month period 10 11. Current SARS registration guidance administers a R2.3 million threshold for specific operational registration workflows, whereas older guides retain the R1 million benchmark 10 12.
This variance represents SARS's administrative position and operational practice; it does not constitute an unqualified statutory amendment to Section 23 of the VAT Act, nor did the Rates and Monetary Amounts Act amend Section 23 10.
Evolv Accountants recommends that SMEs complete bank detail updates well in advance of filing a refund-yielding VAT201 return to avoid administrative delays 1 2.
— Practical point from this guide
Gather approvals and current records: verified bank details
Corporate consents and identity evidence
Before initiating a banking detail amendment with SARS, the enterprise must assemble complete documentation:
- Corporate approvals: A formal company resolution or authority signed by directors or members authorising the bank account change 5 6.
- Bank account confirmation: A bank-issued confirmation letter or stamped statement matching the registered name or trading name of the vendor 13 14 15.
- Identity proof: Identity documentation for the appointed representative vendor 1 16.
Representative vendor duties and third-party account rules
Under South African tax law, the representative vendor (such as a public officer for a company or liquidator for a company in liquidation) is legally accountable for performing statutory VAT duties 16 17. A registered tax practitioner may assist under a valid Power of Attorney (POA), but cannot sign bank detail changes or registration declarations on behalf of the vendor 18 19.
To prevent refund fraud, SARS strictly prohibits paying VAT refunds into third-party bank accounts 5 20 21. Third-party accounts are permitted solely in two specific circumstances:
- Non-resident foreign companies operating in South Africa 5 20 22.
- Group company structures where a holding or subsidiary company receives refunds on behalf of a group entity 5 20 22.
In both permitted cases, the vendor must furnish an account holder resolution and submit Form VAT119i to indemnify SARS against potential losses 5 6 15.
Update each affected system or register: payment readiness
Mapping independent authority systems
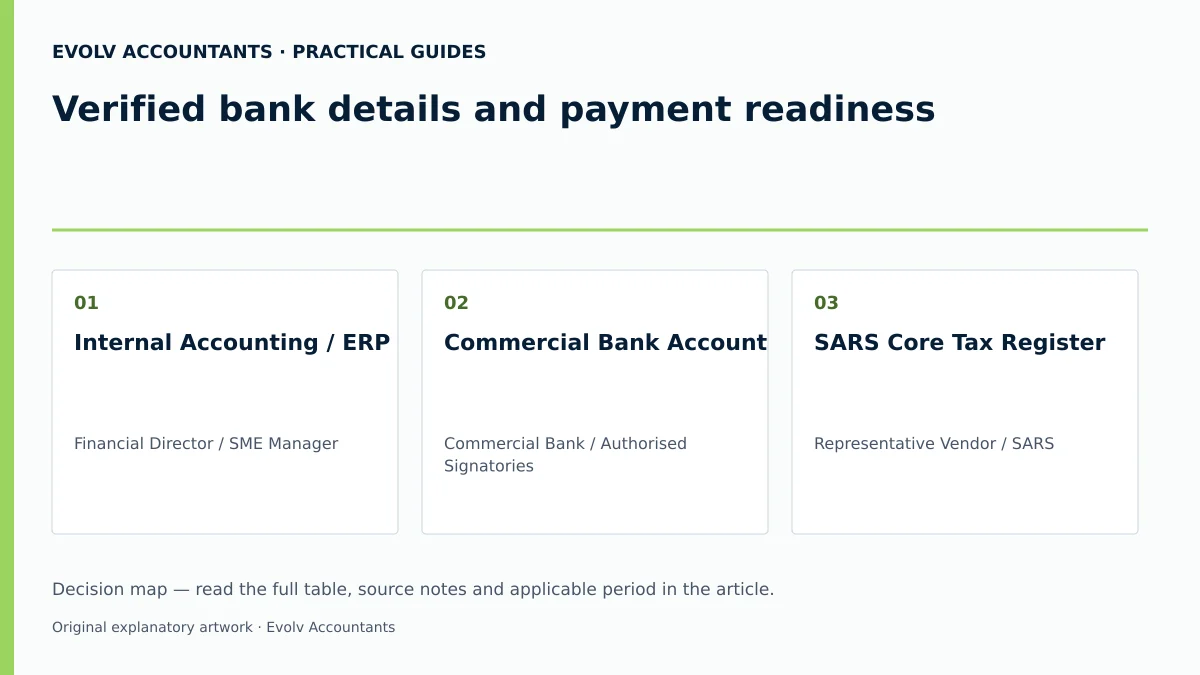
Updating bank details in an SME's internal accounting software or commercial banking portal does not automatically update SARS eFiling or national revenue records 1. Each register operates independently:
- Internal ERP / General Ledger: Controls operational payments and invoice issuance 23.
- Commercial Banking Portal: Executes outgoing payments and receives customer electronic funds transfers (EFTs) 24 25.
- SARS Core Tax Register: Directs output tax credits and statutory refund payouts 1 26 27.
Permitted SARS updating channels
SARS rejects bank detail changes requested over the telephone or via standard email to prevent fraudulent transactions 1 21. Amendments must be lodged exclusively through approved channels:
- SARS Branch Office: Visiting a branch in person (the preferred channel) by making a virtual or branch appointment on the SARS website 1 28.
- SARS eFiling: Submitting updates electronically through the Registration, Amendments and Verification (RAV01) form on eFiling 1 29.
Supporting evidence (bank stamped letters, ID copies, entity certificates) must be uploaded via eFiling or the SARS Online Query System 14 30.
Confirm the change took effect: verified bank details
Verification acknowledgements and public records
After submitting updated banking particulars, vendors must verify that SARS has updated its core tax register before submitting a refund return 1 2. Confirmation can be established through:
- Viewing updated profile details on the eFiling banking particulars container 1 15.
- Inspecting status updates on the VAT Work Page or Refund Dashboard on eFiling 7 31.
- Requesting an official VAT Statement of Account (VATSA) electronically via eFiling or from the SARS Contact Centre 32.
Suspension of the statutory refund processing window
When a vendor is entitled to a net VAT refund, SARS is required to disburse the payment within 21 business days of receiving a correctly completed VAT201 return 2 33 34 35. If SARS fails to pay within 21 business days, interest accrues at the prescribed rate 2 31 34 35.
If banking details are unverified, missing, or incorrect, SARS recalculates or suspends the 21 business day period without interest obligation until valid banking particulars are verified 2 3 4. Other statutory grounds for withholding refunds include outstanding VAT returns, unfinalised verification/audits, or defective returns 2 3 4.
Opening bank balances and refund receipts must be reconciled against VAT201 Field 20 amounts upon disbursement 36 37.
Responsibilities that continue after the change: payment readiness
Ongoing filing liabilities and submission deadlines
Updating banking details does not alter statutory filing obligations. Vendors must submit periodic VAT201 returns by prescribed deadlines:
- Manual branch filings: Due by the 25th day of the calendar month following the tax period 38 39.
- eFiling submissions: Due by the last business day of the calendar month following the tax period 38 39 40.
Late payments attract an immediate 10% administrative penalty plus statutory interest 33 34 41.
Record retention and statutory limitations
Vendors must retain all tax invoices, bank statements, declarations, and proof of payment for at least 5 years 42 43 44.
Key statutory limitations include:
- Refund claims: VAT refunds must be claimed on a return submitted within 5 years from the due date 45 46.
- Input tax deductions: Input tax must be claimed within 5 years from first entitlement 47 48 49. Subsequent revisions to past VAT201 returns cannot increase input tax claims; unclaimed input tax must be deducted on a future return 47 48.
- Debt equalisation: SARS applies statutory set-off, deducting outstanding tax debts from VAT refunds across main and branch registrations before releasing remaining funds 45 46.
Next steps for VAT refunds
Accountable handover checklist
To execute a seamless bank detail update without deleting historic evidence, SMEs should follow this checklist:
- Audit current records: Assemble bank account confirmation letters, company resolutions, and representative vendor ID documents 5 14 16.
- Verify SARS details: Access eFiling to review current registered banking details and identify outstanding returns 1 2 50.
- Submit change request: Lodge updated banking particulars via eFiling or at a SARS branch with supporting evidence 1 14.
- Monitor confirmation: Review the VAT Work Page and Refund Dashboard on eFiling until status reflects verified bank details 7 31.
- File VAT201 return: Submit the current tax period VAT201 return once bank details are active to ensure payment within 21 business days 2 35.
- Archive audit trail: Securely store all submission receipts, VAT201 declarations, and bank confirmations for the mandatory 5-year period 42 43 44.
Change and handover tracker
| Affected record | Authority or owner | Effective date | Action | Confirmation and continuing duty |
|---|---|---|---|---|
| Internal Accounting / ERP | Financial Director / SME Manager | Date of corporate resolution | Update vendor bank master file for client/supplier EFTs | Reconcile monthly bank feeds; maintain 5-year audit trail 42 43. |
| Commercial Bank Account | Commercial Bank / Authorised Signatories | Date account opened | Activate new account; maintain old account until SARS transfer | Verify clearing limits; monitor incoming/outgoing EFTs 24 51. |
| SARS Core Tax Register | Representative Vendor / SARS | Date SARS verification completed | Submit RAV01 via eFiling or visit SARS branch with docs 1 29 | Verify bank status on VAT Work Page; maintain 21-day change duty 7 8. |
| VAT201 Return Register | Public Officer / Evolv Support | First day of month post tax period 52 | Declare Output (Part A) and Input (Part B) tax on eFiling 36 53 | Track 21 business day refund processing timeline 2 35. |
Reproducible hypothetical example
Scenario: Apex Industrial Supplies (Pty) Ltd, a registered South African SME vendor on Category A (bi-monthly tax period), opens a new commercial bank account. The public officer submits bank update documentation via eFiling 1 16. SARS confirms verification on the eFiling profile 7.
For the current tax period, Apex calculates its VAT liability on form VAT201 as follows:
- Part A (Output Tax):
- Standard rated supplies (15% VAT): Consideration of R100,000 in Field 1; Output tax of R15,000 in Field 4 54 55.
- Total Output Tax (Field 13) = R15,000 36 53.
- Part B (Input Tax):
- Standard rated capital goods/services (15% VAT): R200,000 consideration in Field 15; Input tax deduction of R30,000 in Field 15 54 56.
- Total Input Tax (Field 19) = R30,000 36 53.
- Net Calculation (Field 20):
- Field 20 = Total Output Tax (Field 13) minus Total Input Tax (Field 19) = R15,000 - R30,000 = -R15,000 36 37.
- The negative result indicates a net refund of R15,000 due from SARS 37 57.
Apex submits the return via eFiling on the last business day of the month 38 40. Because banking details were verified prior to return submission, SARS processes the R15,000 refund directly into Apex's new bank account within 21 business days without withholding or recalculation 2 33 35.
Frequently Asked Questions
1. How long does SARS take to pay a VAT refund after bank details are updated?
Once valid bank details are verified on SARS systems, SARS must pay valid VAT refunds within 21 business days of receiving a correctly completed VAT201 return 2 33 35. If details remain unverified, the 21 business day counter is suspended 2 3.
2. Can SARS pay our company's VAT refund into a director's personal bank account?
No. SARS strictly prohibits paying VAT refunds into third-party accounts to prevent fraud 5 20 21. Third-party payouts are restricted solely to foreign entities or group companies (holding/subsidiary) supported by Form VAT119i indemnity 5 6 22.
3. What happens if we submit a refund return before updating our bank details?
SARS will withhold the refund payout until valid banking details are submitted and verified 2 4. The statutory 21 business day period is recalculated or suspended without SARS being liable for interest during the delay 2 3.
4. Can a tax practitioner sign the SARS bank update declaration on our behalf?
No. Under SARS regulations, the declaration must be signed by the individual owner, partner, or appointed representative vendor (public officer) 17 19. A tax practitioner cannot sign bank change or registration declarations 19.
5. How far back can we claim unclaimed input tax on past purchases?
Vendors may deduct unclaimed input tax on a future VAT201 return up to 5 years from the date of first entitlement 47 48 49. Unclaimed input tax cannot be added by revising past returns 47 48.
Related guides
- Why a VAT refund can be delayed
- Documents SARS may request during VAT verification
- The Proactive SARS Audit Guide: Keeping Your Business Ledger Sanitised
Sources
- https://www.sars.gov.za/wp-content/uploads/Ops/Guides/Legal-Pub-Guide-VAT404-VAT-404-Guide-for-Vendors.pdf
- VAT Refunds for vendors | South African Revenue Service
- https://www.sars.gov.za/wp-content/uploads/Ops/Guides/VAT-REG-02-G01-Guide-for-Completion-of-VAT-Application-External-Guide.pdf
- https://www.sars.gov.za/wp-content/uploads/Ops/Guides/GEN-ELEC-04-G01-Guide-for-completing-the-Value-Added-Tax-VAT201-Declaration-External-Guide.pdf
- FAQs for VAT vendors | South African Revenue Service